

Wells Fargo's Divergent Energy Ratings: BP vs. Exxon
Saturday, October 03, 2026
WELLS FARGO'S DIVERGENT ENERGY RATINGS: BP VS. EXXON
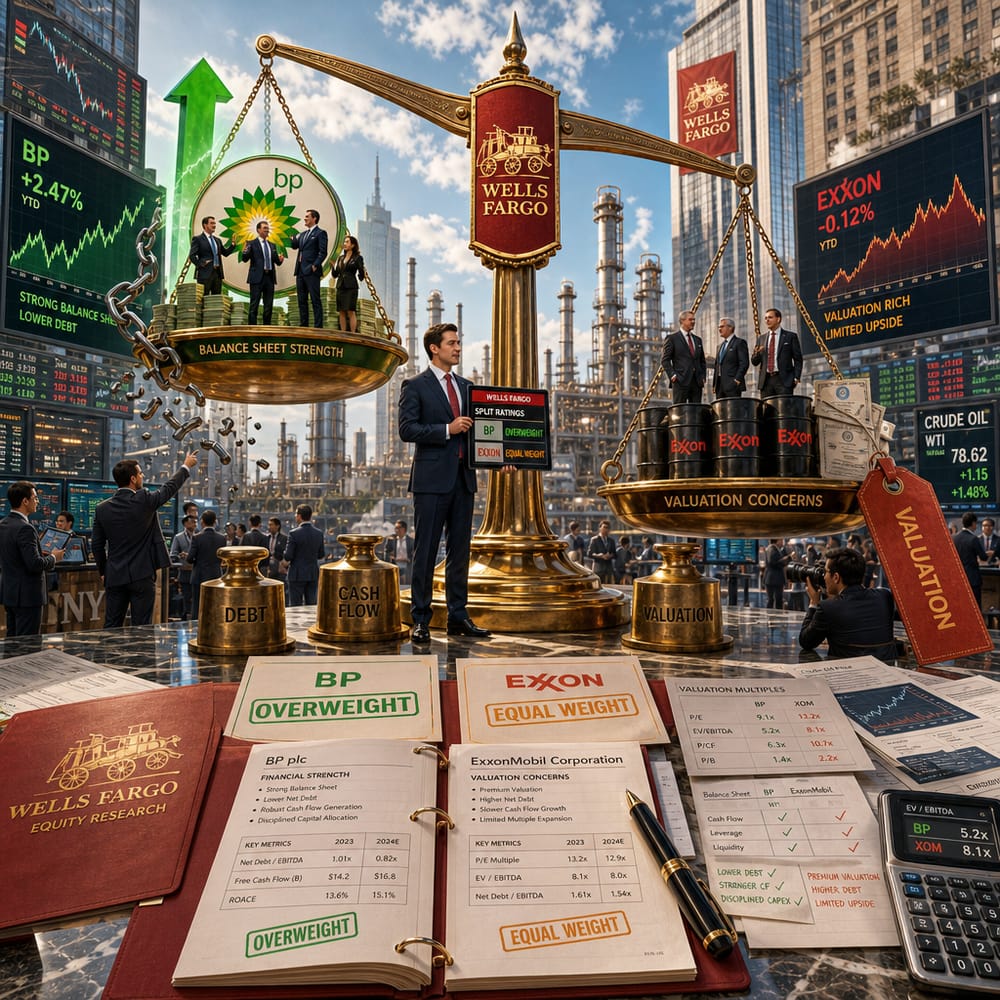
In the world of big oil, Wells Fargo just played matchmaker, and guess who got the rose? BP. Meanwhile, Exxon Mobil found itself downgraded, left holding a wilted bouquet. So, what’s driving this newfound romance with BP, and why is Exxon feeling the chill?
First things first, let’s talk BP. Those fun-loving folks at Wells Fargo decided BP deserves an "Overweight" rating. Nope, this isn't a comment on BP’s carb intake—it’s a vote of confidence, signaling potential weighty returns for investors. The reason behind this upgrade? BP has been hitting the gym, shedding debt faster than we’re shedding cash on $4-a-gallon gas. With its balance sheet looking leaner than a marathon runner at the finish line, BP appears primed for a strong performance.
BP’s financial finesse comes just in time as the energy sector is playing a game of Goldilocks with valuations—trying to find the one that’s just right. BP is managing to look attractively priced, avoiding the bloat some of its competitors are battling. It’s a bit like finding a designer jacket at a thrift store—quality at a steal.
Now, let’s look at our friend Exxon Mobil, who’s currently experiencing a bit of a Cinderella moment as the clock strikes midnight. Wells Fargo slapped it with an "Equal Weight" rating. In plain English, that means Exxon isn’t expected to outperform the market. Why the sudden pumpkin status? It’s all about valuation, baby. Exxon’s stock price has been acting like your uncle at a wedding—rising too high and too fast.
Compared to its peers, Exxon is starting to look a tad pricey. While Exxon has been strutting its stuff confidently, its valuation is making some investors feel like they’ve already shelled out for the filet mignon only to receive a hamburger. Classic bait-and-switch.
What does this mean for investor sentiment in the energy sector? Well, BP’s upgrade might boost its attractiveness as a golden goose for investors looking for growth without the hefty price tag. Meanwhile, Exxon may have to adjust its crown as investors question whether it's worth its current weight in gold. It’s the classic case of the tortoise and the hare, where the tortoise (BP) might just win the race in the eyes of discerning investors.
The shift in ratings is like a juicy plot twist in the soap opera of the energy market. BP’s improving financial health and favorable valuations make it the new darling. At the same time, Exxon may need to prove it’s not just riding high on past glories if it wants to regain favor.
Let’s be honest, folks. The energy sector is filled with drama, intrigue, and more twists than a pretzel factory, and these moves by Wells Fargo add another chapter to the saga. For investors, the message is clear: BP is the current star to watch, while Exxon might need a little more than its legendary name to keep the spotlight.
In the end, whether you’re swooning over BP’s financial prowess or cautiously optimistic about Exxon finding its footing, it’s a reminder to always do your homework. Because in the high-stakes world of energy stocks, the plot can change faster than you can say “barrel of oil.” So, keep your eyes peeled and your portfolios ready—there’s always more to come.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.