

Vistra's Strategic Buyback and Upgraded Guidance
Monday, November 09, 2026
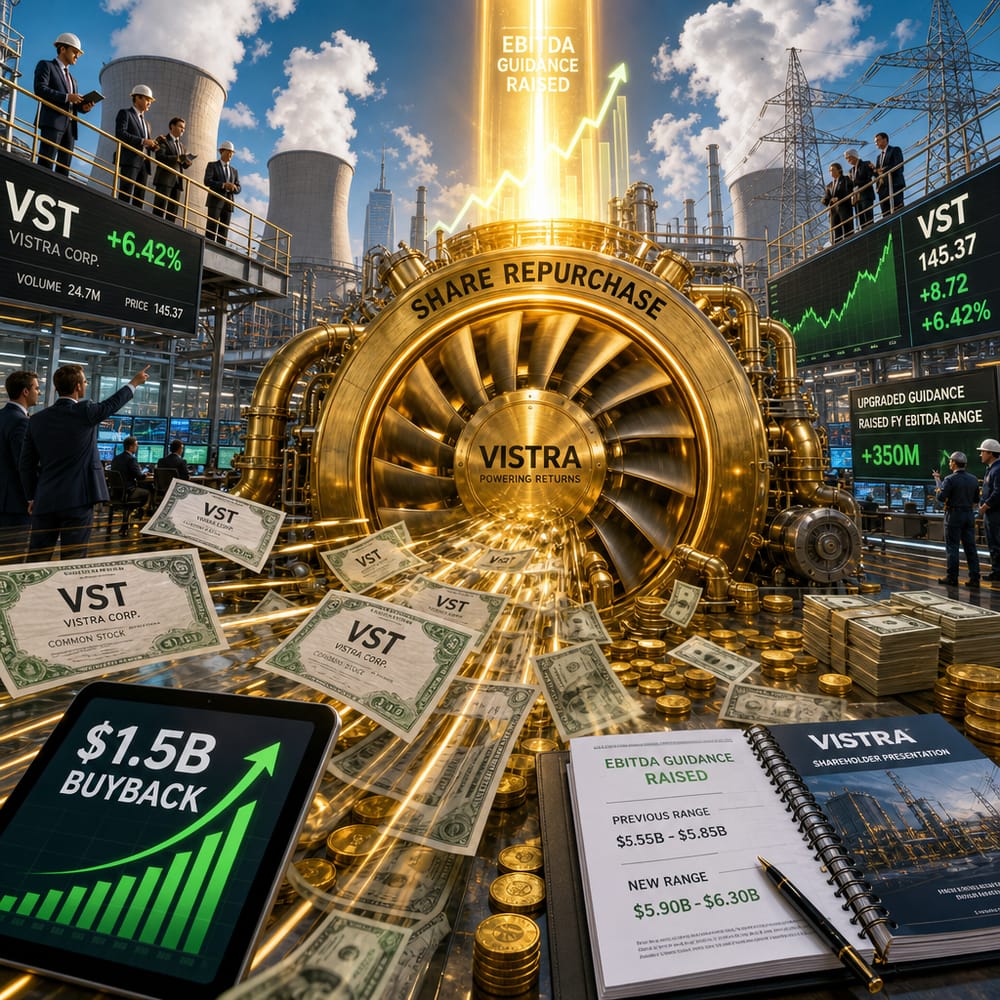
VISTRA'S BIG PLANS: BUYBACKS AND BOOMING EXPECTATIONS
Brace yourselves, Vistra fans. The energy powerhouse just threw a financial cocktail party and served up a double shot of goodness: a $1.5 billion share buyback and a juicy upgrade to their EBITDA guidance. If that sentence just made you choke on your morning coffee and ask, “What does that mean for me?” — you’re in the right place. Let’s break it down.
First, imagine a company’s stock as a pie. When a company like Vistra buys back shares, they’re essentially taking a slice out of that pie and eating it themselves. This leaves fewer slices (shares) for everyone else — meaning each slice gets bigger. For you, dear investor, this translates to owning a larger piece of the pie without lifting a finger. It's a classic maneuver for companies that are cash-rich and confident in their financial future. Vistra’s decision to gobble up some of its shares to the tune of $1.5 billion isn’t just a random act of kindness. It’s a loud and clear signal to the market that they believe their stock is undervalued and poised for growth.
But let's talk history for a minute. Vistra isn’t a stranger to capital return strategies. This isn’t their first buyback rodeo, and their past efforts have often paid off, providing a boost to their stock price and investor satisfaction. However, this latest move is a more aggressive play, indicating that they’re not just hopeful about future earnings — they’re downright bullish. They want investors to buckle up because they believe good times are ahead.
And speaking of good times, Vistra also sweetened the deal with an upgraded EBITDA forecast. If you’re wondering what EBITDA is, it's a fancy financial term that stands for Earnings Before Interest, Taxes, Depreciation, and Amortization. It's basically a way to measure a company’s performance without getting bogged down by accounting nuances. Raising this guidance suggests Vistra expects their core business to do better than previously anticipated.
Now, why should you care about this EBITDA upgrade? In simple terms, it means Vistra is projecting more earnings muscle, which usually translates to a higher stock valuation. If the company has more robust cash flows and profitability, it can invest in new projects, pay down debt, or, you guessed it, do more stock buybacks. This rosy outlook can send stock analysts and investors into a tizzy of excitement, often driving up the stock price.
So, what do the analysts think? Well, they’re mostly nodding in agreement, with a few giving Vistra an enthusiastic thumbs-up. Analysts love a story of resilience and growth, especially when it’s backed by concrete financial plans like buybacks and upgraded guidance. It’s like corporate catnip. They see Vistra’s moves as a positive reinforcement of the company’s long-term strategy and financial health.
But, and there’s always a but, the markets are anything but predictable. While Vistra’s announcements are encouraging and signal confidence, broader market conditions, geopolitical tensions, or even the mood swings of Wall Street traders can affect stock performance. Right now, the markets are eyeing inflation, interest rates, and geopolitical headlines like a hawk. While Vistra’s strategy seems rock solid, the market’s reaction will also depend on external factors beyond the company’s control.
In conclusion, Vistra is rolling the dice on its future with a big bet on buybacks and a cheerful tweak to its profit forecasts. For investors, this is a reason to smile and perhaps consider whether Vistra deserves a bigger spot in their portfolio. Whether you’re a cautious investor or the kind who enjoys a bit of a thrill, keep an eye on how these strategies play out in the coming months. Vistra has set the stage — now it's time to see if the market applauds.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.