

Treasury Yields Surge to Two-Decade Highs on Policy Uncertainty
Monday, August 17, 2026
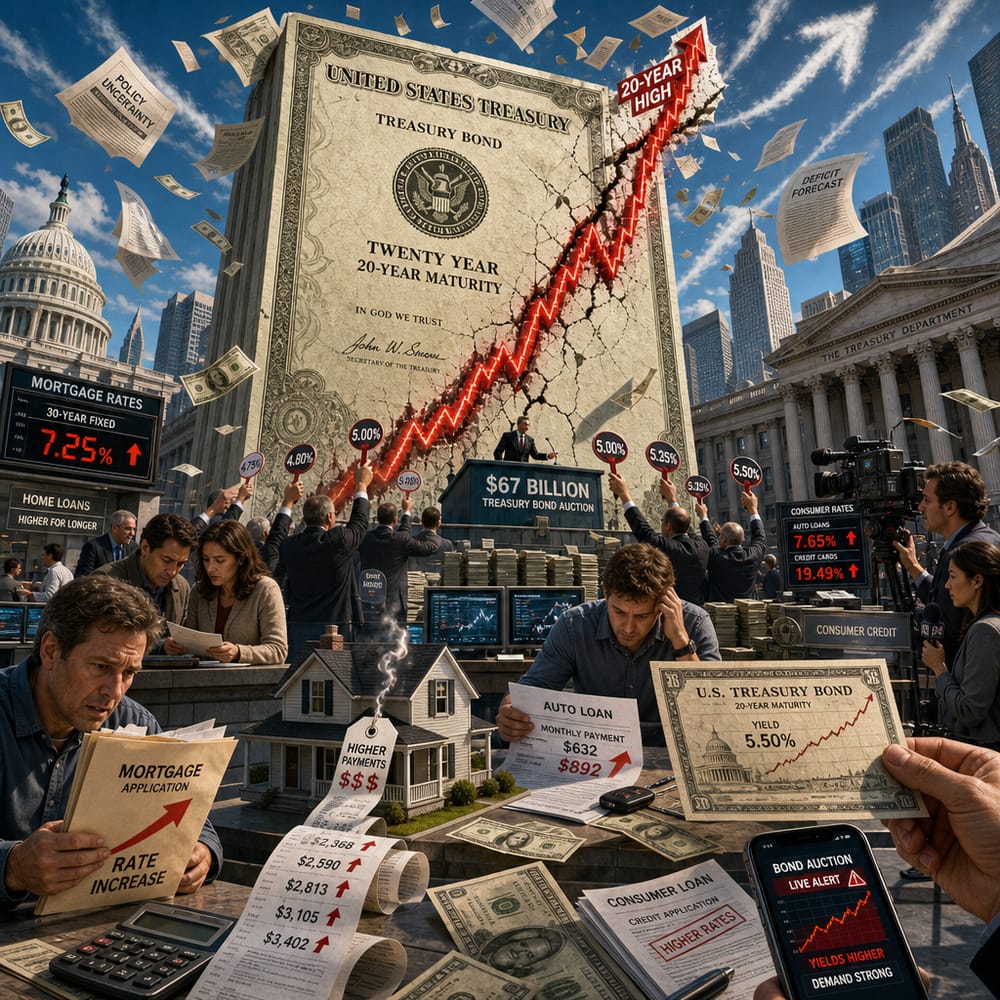
TREASURY YIELDS SOAR TO TWO-DECADE HIGH: WHY IT’S ABOUT TO HIT YOUR WALLET
Well, folks, Uncle Sam’s borrowing spree is looking more like a high-wire act without a safety net. Investors are demanding the highest yields—think interest payouts from bonds—in nearly two decades just to consider buying long-term U.S. government bonds. A staggering $67 billion of these suckers just hit the market, and it seems people are more skittish than a cat on a hot tin roof. But what does this mean for you, your mortgage, and just about every loan with a pulse? Let’s roll up our sleeves and dig in.
The Fed’s financial wizardry—or lack thereof—has everyone from Wall Street bigwigs to your kid’s lemonade stand re-evaluating their next move. With Treasury yields climbing like they’ve just guzzled a gallon of energy drink, borrowing costs are shooting up across the board. If you’re eyeing a swanky new car or dreaming about that cute little cottage with a white picket fence, brace yourself. Loans are about to get pricier than a designer coffee habit.
Here’s why you should care: When the government pays higher yields on its debt, it sets a benchmark for interest rates all over. Those Treasury yields aren’t just collecting dust in a vault; they’re the bedrock of our financial system. Mortgage rates, auto loans, credit card APRs—they all take their cue from this financial cornerstone. And when it shifts, it’s not just a stone in the pond; it’s a tidal wave.
Imagine this: You’re planning to buy a house. Maybe you’ve got your eye on a quaint little place with just enough space for a garden. But here’s the kicker: rising Treasury yields could make your mortgage climb faster than your favorite cat up the drapes. Suddenly, that affordable dream home is a financial squeeze.
And it’s not just homeowners feeling the pinch. Businesses big and small are staring at their ledgers with more wrinkles on their foreheads than a shar-pei puppy. Companies rely on borrowing to expand, innovate, and sometimes just keep the lights on. Higher interest costs mean they might have to tighten their belts, raise prices, or even hit the pause button on growth. Not exactly a recipe for economic dynamism.
But let’s back up a second. Why are these yields on the rise? Two big words: policy uncertainty. The Federal Reserve, that enigmatic body of financial alchemists, has been sending mixed signals about its future moves. Will it keep interest rates where they are? Jack them up some more? Maybe even take a breather? This unpredictability is making everyone as jittery as a coffee lover at an espresso festival.
As borrowing costs soar, consumers might start clutching their wallets as if they’re holding the last golden ticket. Spending, which keeps our economic engine humming, could hit a speed bump. Smaller purchases might get nixed, big-ticket items postponed. It’s a domino effect—you cut spending, businesses earn less, they cut costs, and suddenly, the economy starts looking a lot like it’s had one too many.
So, what do we do? Businesses might get creative, shifting gears in their financing strategies. They could lock in lower rates now before things get more chaotic, or trim the fat to preserve cash. As for us everyday folks, it might be time to reassess those financial aspirations. We could hold off that big purchase or shop around for the best loan deals like it’s Black Friday.
High Treasury yields are more than just numbers flashing on a screen—they’re financial ripples that touch every corner of our lives. From how much you pay for your house to how companies budget their next fiscal year, these yields pack a punch. As the dust settles, we’ll keep our eyes glued to how this unfolds. Your wallet might not thank you for it, but being informed never hurt anybody.
So, as you sip your morning coffee and swipe through your phone, remember: those little numbers have big implications. Stay sharp, stay informed, and above all, stay financially savvy.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.