

Treasury Yields Cross 5%: Implications for Borrowers and Budgets
Wednesday, September 23, 2026
TREASURY YIELDS CROSS 5%: IMPLICATIONS FOR BORROWERS AND BUDGETS
The bond market just threw a party and nobody wanted to come — except rising Treasury yields, crashing through the roof at over 5%. That's the kind of headline that can make even the calmest of investors spill their coffee. But what does it all mean for those of us not on Wall Street? Let’s break it down.
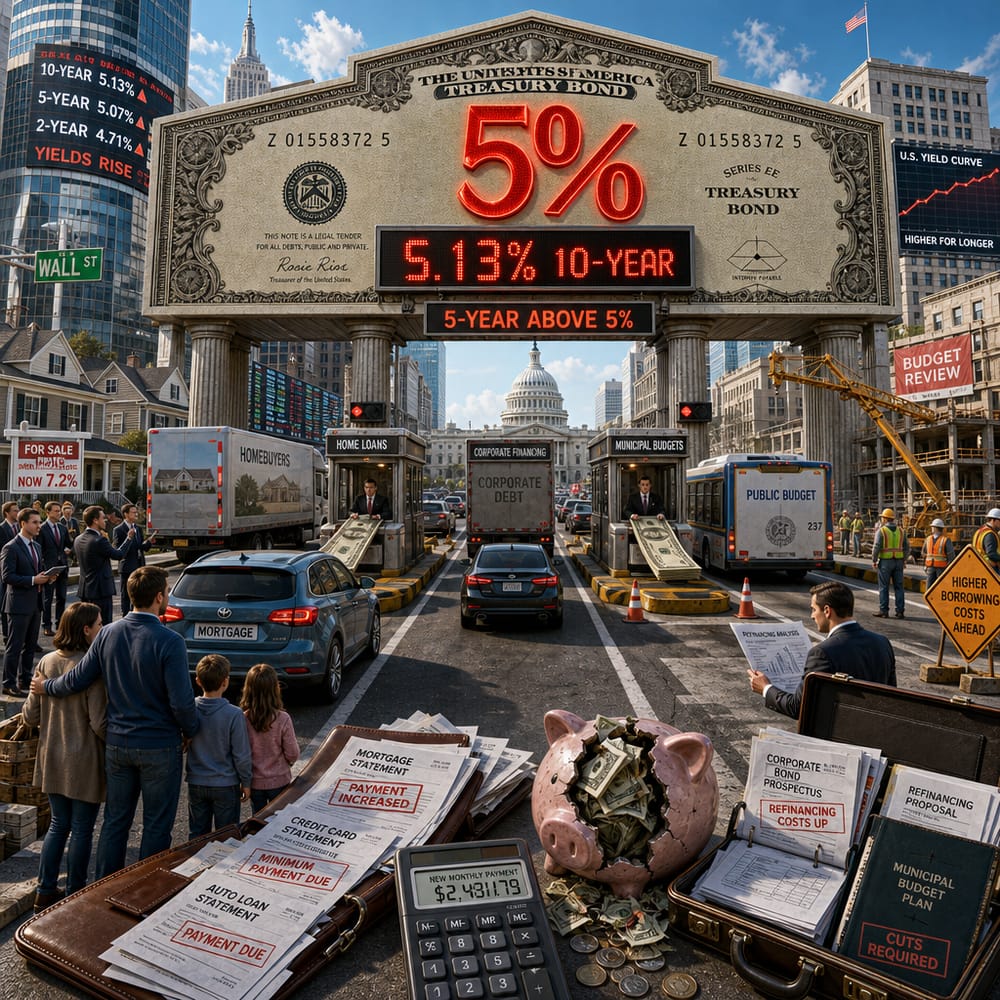
Treasury yields are like the quiet kid in the back of the class. Most of the time, they don’t get noticed unless they throw a real tantrum. And right now, they’re in full meltdown mode. The 10-year yield hitting 5.13% and the 5-year yield snapping past 5% isn't just a boring number; it's a warning sign that financial conditions are tightening faster than your belt after Thanksgiving dinner.
So why should you care? For starters, this yield spike isn't just academic. When Treasury yields go up, so do borrowing costs. Imagine climbing a steep hill with a backpack full of bricks — that's what higher yields do to loans, mortgages, and credit. They make everything more expensive.
And if you're a homeowner with an adjustable-rate mortgage or thinking about buying a house, brace yourself. The cost of borrowing money for that white picket fence just went up. Mortgage rates are highly sensitive to Treasury yields, meaning your monthly payment could feel heavier than that backpack.
The impact doesn't stop at your doorstep. Corporations are feeling the heat too. Higher yields translate to higher borrowing costs for companies. For those businesses used to cheap money, this is like going from happy hour prices to paying full price at the bar. It could mean cutting back on expansion plans or scaling back hiring — neither of which spells good news for the economy.
Now, let’s talk about Uncle Sam — the U.S. government. With the federal debt sitting at a breezy $40 trillion, higher yields mean higher interest payments. Imagine if your credit card interest rate shot up overnight; that’s what’s happening on a massive scale. It could force some tough choices in Washington, potentially impacting everything from infrastructure projects to social programs.
For the everyday investor, you might be wondering if there's a silver lining in these storm clouds. Savers could see slightly better returns on their savings accounts or CDs. However, don’t start planning that dream vacation just yet — the increases are usually modest.
But if you’re the type who’s attracted to bonds like a moth to a flame, it might be time to pay attention. Higher yields mean bonds are offering better returns. It’s like bonds going on sale at the investment mall — but caution is key. As with all investments, higher potential returns come with higher risks.
From the Federal Reserve's perspective, this yield spike might just fan the flames of a rate hike debate. With inflation pressures still simmering, the Fed could be convinced to lift interest rates higher to keep inflation in check. It’s a delicate balance, and one that could ripple through the economy.
So what's the bottom line? Rising Treasury yields might seem like a snooze-worthy topic, but their impact is anything but boring. They touch nearly every aspect of the financial world, from your personal budget to corporate balance sheets, and even the federal budget. It’s a reminder that in the interconnected world of finance, no change is without consequence.
In short, keep an eye on those yields. Whether you're a saver, a spender, or a policy wonk, they're something you can't afford to ignore.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.