

Treasury Yields Climb: Signals of Fed Hawkishness and Inflation Risk
Thursday, August 06, 2026
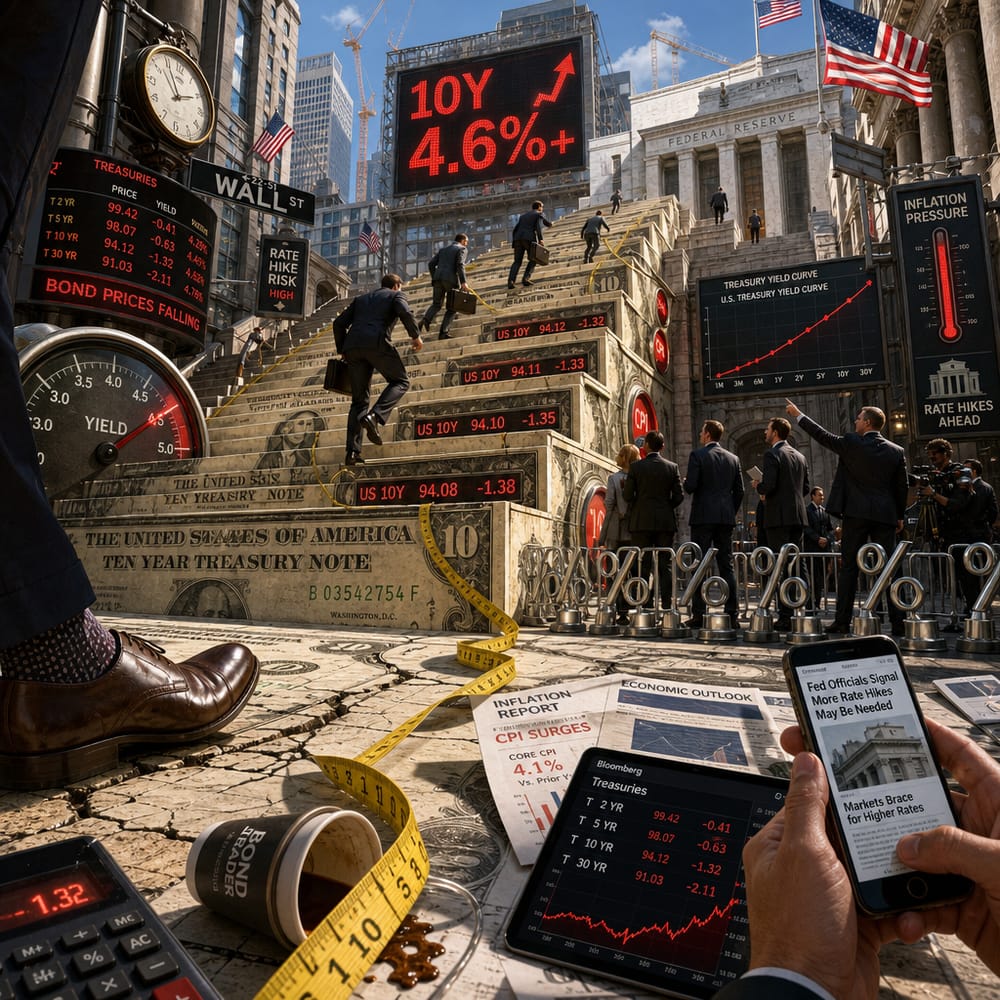
TREASURY YIELDS CLIMB: SIGNALS OF FED HAWKISHNESS AND INFLATION RISK
We interrupt your regularly scheduled scroll through cute cat videos to bring you some financial news that's just as attention-grabbing. Imagine a party where everyone's talking about inflation and interest rates. Boring, right? Until you realize that's the party determining your mortgage rate, the cost of your car loan, and even the value of your retirement portfolio. Say hello to the 10-year Treasury yield, your new best frenemy.
The 10-year Treasury yield, a key barometer for financial markets and your wallet, has recently soared past 4.6%. For the uninitiated, Treasury yields are essentially the interest the government pays you for loaning it money. When these yields rise, like they've been doing, it often signals inflation worries and the possibility of the Fed throwing a few more rate hikes your way.
So, what's causing this upward climb? Well, it seems to be a cocktail of inflation paranoia and hints of a hawkish Federal Reserve, a term used when the Fed is in a mood to crank up interest rates to cool things down. Picture the Fed as the designated driver at the economic party, always ready to take away the punch bowl of cheap money just when everyone's starting to have fun.
But why should you care if these yields are on the rise? Because when Treasury yields go up, borrowing costs can follow suit—it's like gravity, but for money. Your dream of upgrading from a 2008 clunker to a Tesla might suddenly get pricier. Ditto for that cozy new home you’ve been eyeing. Basically, it's Uncle Sam’s way of gently reminding you that nothing in life is free, especially not money.
The ripple effects of these rising yields extend to different sectors in various ways. Utilities, those stalwart favorites of yield-hungry investors, might suddenly look like old news. Who needs a steady 3% dividend when you could play it safer with government bonds? Financials, on the other hand, may just throw their own party. After all, banks make their money on the spread between what they pay you for your savings account (spoiler: not much) and what they can charge borrowers. Higher yields could fatten those margins nicely.
Tech stocks—poor babies—are feeling the pinch. Rising rates often clobber tech shares because future profits are worth less in today's dollars as borrowing costs hit the stratosphere. It's a bit like being asked to pay for a meal now that you won't eat until 2030. Understandably, not everyone’s thrilled.
And let's not forget housing. Remember when your realtor said interest rates were historically low, practically begging you to buy that "fixer-upper with potential"? Well, those days might not be gone, but they're certainly packing for a vacation. Rising Treasury yields often lead to higher mortgage rates, which has a tendency to cool off red-hot housing markets faster than an unexpected snowstorm at a summer picnic.
So, what's the average Joe or Jane investor to do in this yield-rising scenario? You might want to dust off your old financial plan or, gasp, consider creating one if you haven't already. Diversify your investments, perhaps give dividend stocks and bonds another look—or simply take a breather from market madness and keep some cash handy. After all, peace of mind is a pretty good return on investment.
While the Fed's upcoming moves remain as uncertain as reality TV plot twists, one thing's for sure: Paying attention to these yields isn't just for Wall Street wizards. It’s for anyone with skin in the economic game. And let's face it, that includes all of us, whether we're financial gurus or simply trying to keep our latte budgets intact.
In the world of finance, where acronyms fly faster than birds, keeping an eye on the 10-year Treasury yield is akin to checking the weather forecast. You might not be able to control it, but with a little foresight, you can at least decide if it's a day for sunglasses or a sturdy umbrella. So keep those eyes peeled and wallets ready, because when it comes to Treasury yields, ignorance is definitely not bliss.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.