

Treasury Yield Volatility Put Markets on Thin Ice Through Quarter-End, But Buyers Returned as Rates Cooled
Sunday, October 04, 2026
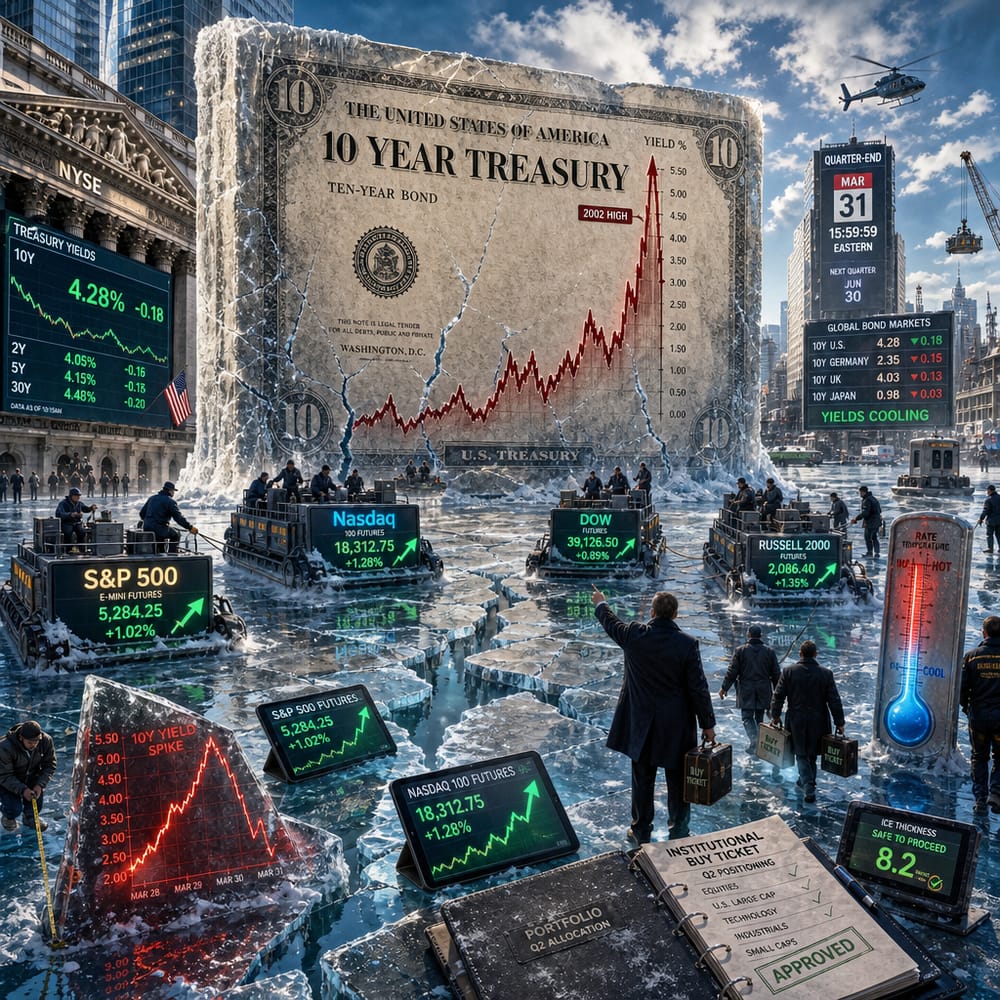
WHEN TREASURY YIELDS GO WILD: A VOLATILE RIDE FOR INVESTORS
Just when you thought you had the market figured out, the 10-year Treasury yield decides to throw a curveball at your portfolio. Like a surprise snowstorm that hits on an otherwise perfect autumn day, high Treasury yields have been stirring up trouble on Wall Street. Up to their highest levels since 2002, these yields are playing havoc not just with bond prices, but with equities too. Let's break it down.
First, a quick refresher for those who've tuned out to catch up on the latest season of "The Great Portfolio Bake Off": Treasury yields are essentially the interest rate the government pays you for lending it money. When they're high, it means the government needs to offer more to borrow, usually due to investor anxiety about the economy or expectations of future interest hikes by the Fed. This time, the yields shot up like they were powered by an espresso-fueled trader.
So why do these soaring yields matter for your stock investments? Simple. High yields make bonds more attractive versus stocks. Imagine a see-saw: when one side goes up (yields), the other one (stocks) often goes down. This time, the specter of those lofty yields had equity markets clutching their pearls well into the end of the quarter.
But just as we were getting used to clutching our pearls, yields cooled off slightly, coaxing equity futures to rebound. If you're wondering why investors acted like the market just announced a flash sale, it's because lower yields often ease the pressure on growth sectors like tech and smaller caps found in the Nasdaq and the Russell 2000. These sectors thrive on cheap borrowing costs, and when rates rise, their future profits look a bit shakier. But when the yields back off? It's back to optimism-town.
Different sectors react differently to these yield swings. Tech stocks, for example, tend to sulk when yields go high because their often long-term profit horizons look less appealing against the quick, juicy returns bonds can offer. Think of it as competing with your neighbor's brand-new convertible when you're driving a sensible sedan. Meanwhile, financials, like banks, often welcome higher rates because they can charge more for loans than they pay for deposits.
But it's not just the sector shuffle you need to consider. Investor sentiment is a fickle beast, and these yield fluctuations have made it even more volatile. With everyone from pension funds to the guy trading stocks in his pajamas keeping an eye on the Fed's next move, any whisper of yield changes can send shivers—or cheers—through the markets.
As we cruise into Q4, the big question is whether the markets can maintain their balance amid this delicate dance between bond market pressures and equity resilience. For now, the S&P 500 and Dow have been holding firm, but it's a thin line.
For retail investors keeping an eye on their portfolios, it's crucial to consider how these yields could impact asset allocation strategies. If you haven't already, it might be time to sit down with your financial advisor and reassess. Are you comfortable with your mix of equities and bonds? Is your exposure to interest-sensitive sectors aligned with your risk tolerance?
The volatility in Treasury yields is a stark reminder that, in the world of investing, nothing is as certain as change. So, keep your ear to the ground, your portfolio diversified, and don't be afraid to ask questions. After all, those who understand the game best are the ones who know how to play it.
In this whirlwind of rates and reactions, it's all about staying informed and being prepared to pivot. Remember, the market's like that unpredictable friend we all have—just when you think you've got them figured out, they go and surprise you. So, stay sharp and stay savvy.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.