

Rising Treasury Yields Defy Cooling Inflation: Term Premium or Deficit Pressure?
Thursday, November 19, 2026
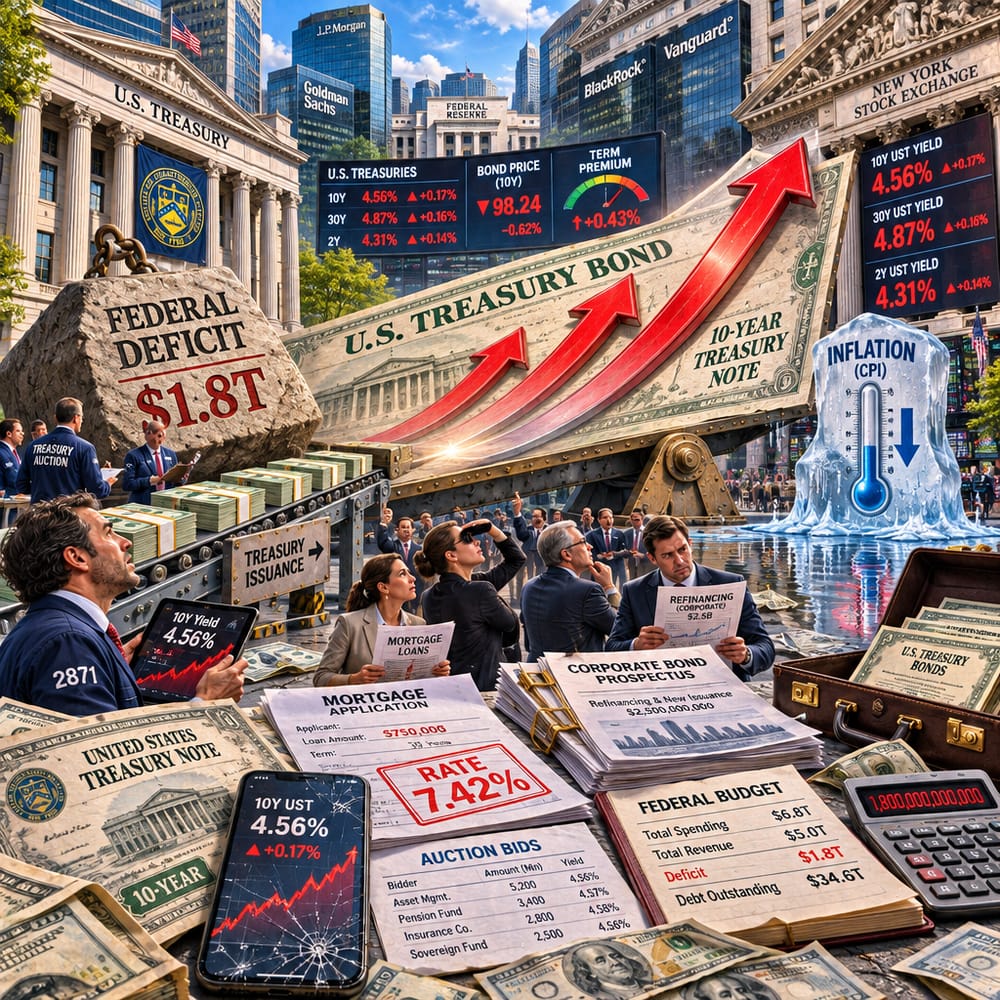
RISING TREASURY YIELDS DEFY COOLING INFLATION: TERM PREMIUM OR DEFICIT PRESSURE?
Imagine if you were baking a cake and despite turning down the oven, it just kept getting hotter. That's the confounding reality currently cooking in the U.S. Treasury market, where yields are rising even though inflation seems to have taken a chill pill. While investors were expecting a mellow market following softer inflation reports, Treasury yields have decided to throw a curveball. So, what's simmering beneath the surface, and why should you, the savvy retail investor, care?
WHAT'S PUSHING TREASURY YIELDS UP?
Let's start with the basics: Treasury yields are essentially the interest rates on U.S. government debt. Typically, when inflation cools, yields tend to ease because investors expect the Federal Reserve to hold off on hiking interest rates. But this time, something's different.
One possible factor at play is the term premium. Think of it as the extra compensation investors demand for holding a longer-term bond compared to rolling over shorter-term bonds. It's like the surcharge you’d charge a friend to hold onto their dog for a year instead of just a weekend. Rising term premiums could suggest investors expect more future inflation or uncertainty, which could be causing this spike in yields.
But wait, there's more. Enter the U.S. government’s hefty borrowing needs. With Uncle Sam issuing truckloads of Treasury bonds to finance a ballooning deficit, yields might be climbing simply because the market's flooded with debt. More supply can mean lower prices and, inversely, higher yields. It's the classic “too much candy, not enough kids” scenario.
HOW MIGHT THIS IMPACT YOU?
Now, you might be thinking, “How does this finance wizardry affect my daily coffee runs?” Well, rising Treasury yields aren't just government business. They ripple through the economy, affecting everything from mortgage rates to corporate loans.
Take mortgage rates, for instance. They tend to move in tandem with Treasury yields. So, as yields climb, expect home loans to get pricier. If you're in the market for a new house or thinking of refinancing, this is your cue to act before costs shoot through the roof.
On the corporate side, companies eyeing expansion or new projects could find borrowing more expensive as well. Higher yields mean higher interest costs for businesses issuing bonds, which could stifle growth and potentially curb stock prices. In other words, if you’re holding stocks in companies that rely heavily on debt, you might want to pay attention.
STOCK MARKET SHUDDER
Let's zoom out to the broader stock market. Rising bond yields usually give stocks a run for their money. Why? Because if bonds offer higher returns, investors might decide to pivot away from riskier stocks towards the safer returns of fixed income. This could explain why the stock market's been a mixed bag lately, with tech stocks enjoying a bit of a boost from the AI craze, thanks to Anthropic's blockbuster IPO, while other sectors stumble.
Moreover, if corporate borrowing costs rise, it could lead to slower earnings growth, affecting stock valuations. The Dow, S&P 500, and Nasdaq could continue their rollercoaster ride, so buckle up if you’re heavily invested in equities.
WHAT’S THE BOTTOM LINE?
As the yield market does its little dance, keep in mind that this isn’t just number-crunching for economists. It’s a reflection of real economic forces and expectations about the future. For retail investors, understanding these dynamics can be the difference between smart investment choices and the equivalent of financial spaghetti on the wall.
Whether it’s deciding to lock in a mortgage rate, considering a shift in your portfolio, or deciphering what that next macroeconomic move means for you, keep an eye on Treasury yields. They might just be the thermometer that helps you gauge the heat in today’s financial kitchen.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.