

Mortgage Rates Hit Year-Long High Amid Fed Caution
Thursday, August 13, 2026
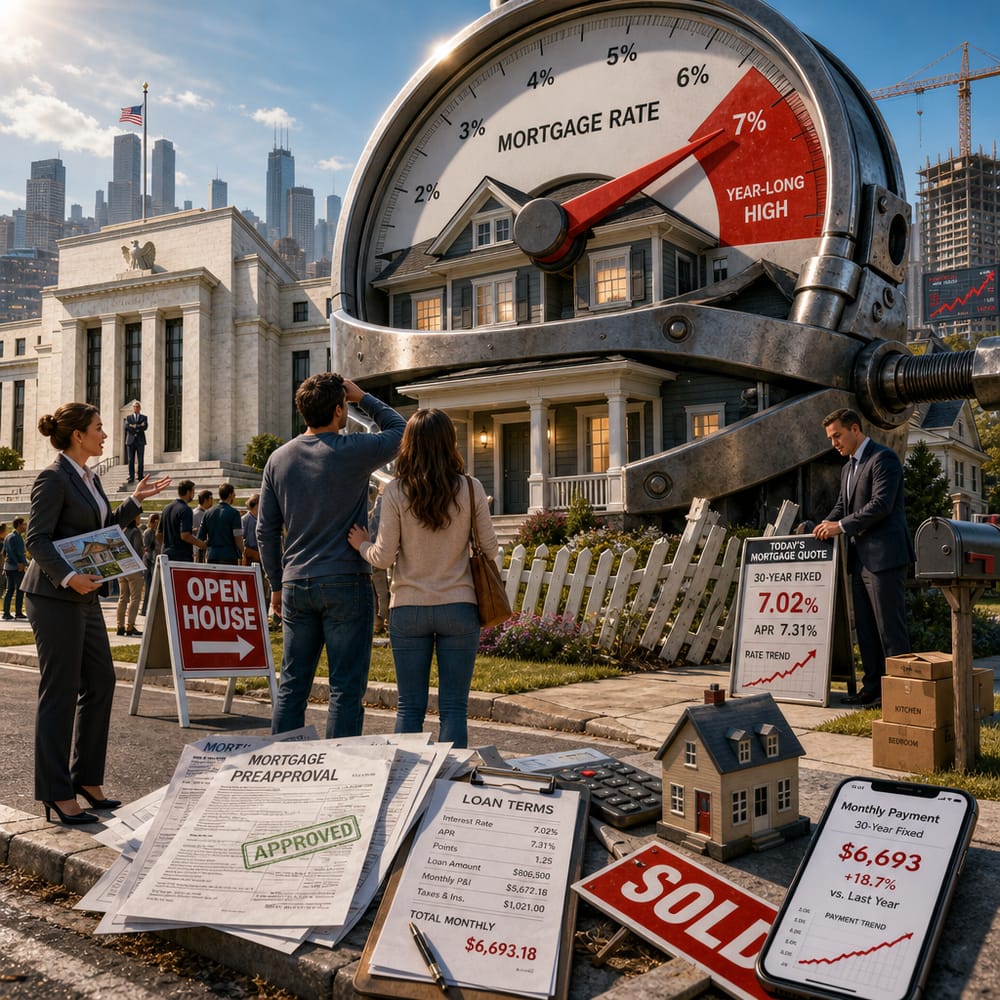
MORTGAGE RATES HIT YEAR-LONG HIGH AMID FED CAUTION
Buckle up, homeowners and wannabe homeowners, because mortgage rates are on a roller coaster ride that just hit a new peak. For the fifth week in a row, U.S. long-term mortgage rates have climbed to their highest level in over a year. If you're feeling hotter than a summer day in Phoenix at the thought of securing a home loan right now, you’re not alone.
So, what's fueling this upward trend? Let's peel back the layers and see what’s cooking in the financial stovetop.
THE HOUSING MARKET DILEMMA
First things first, rising mortgage rates are like kryptonite to the housing market’s superpowers. When rates take an upward stroll, they make homes less affordable for buyers. This price hike can slow down the housing market, making it harder for folks to realize the American dream of owning a white-picket-fence, dog-in-the-backyard kind of home. It’s like showing up to a potluck with a dessert no one can afford to taste.
For those already clutching onto a mortgage, the ripple effects of these rate increases could mean refinancing options are as appealing as stale popcorn. Higher rates shut the door on the chance for many to tap into better loan terms, effectively locking them into their current financial dance.
REGIONAL DISPARITIES: NOT JUST A COASTAL ISSUE
But wait, there's more! The sting of rising rates doesn’t hit everyone equally. Depending on where you park your car at night, mortgage access can feel like either climbing Mount Everest or a breezy beach walk. Coastal cities, often with sky-high property prices, feel the squeeze harder than an overstuffed subway car. Meanwhile, regions with more affordable housing markets might get off with just a pinch.
The uneven impact across different regions means that while some areas cool down like leftover pizza, others might just be getting their dinner parties started. It’s the housing market’s version of a high-stakes game of musical chairs.
THE FED’S HIGH-WIRE ACT
So, what's the Fed’s role in this mortgage rate melodrama? Imagine the Federal Reserve as a tightrope walker trying to balance two massive weights: economic growth on one side and inflation on the other. One wrong move, and it’s a long way down.
The Fed’s cautious approach is heavily influenced by the current inflation narrative. As they tiptoe across the economic tightrope, their efforts to control inflation without stalling growth is like trying to pat your head and rub your belly at the same time. Tricky, to say the least.
Rising rates are a classic Fed tool to cool an economy that’s overheating faster than your laptop running 20 tabs of cat videos. The goal? To keep inflation from spiraling out of control without turning economic growth into a flat tire on the highway of recovery.
LOOKING FORWARD: THE ROAD AHEAD
As we gaze into the crystal ball of the housing market, what can retail investors expect? For starters, a continuing battle between demand and affordability. High mortgage rates might put a damper on the buying frenzy, but they also signal caution from the Fed in an attempt to keep the economy from boiling over.
Investors might need to think regionally—paying close attention to local market dynamics rather than just national headlines. While some areas might feel the brunt of high rates, others could still offer golden opportunities.
So keep your eyes peeled and your financial strategies nimble. As the Fed walks its tightrope, the housing market will continue to evolve, offering both challenges and opportunities for those bold enough to navigate its twists and turns.
It’s a wild ride, but isn’t that what makes the financial world a thrilling place to be?
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.