

Mortgage Rates Climb to Multi-Year Highs as Bond Yields Remain Elevated
Tuesday, August 11, 2026
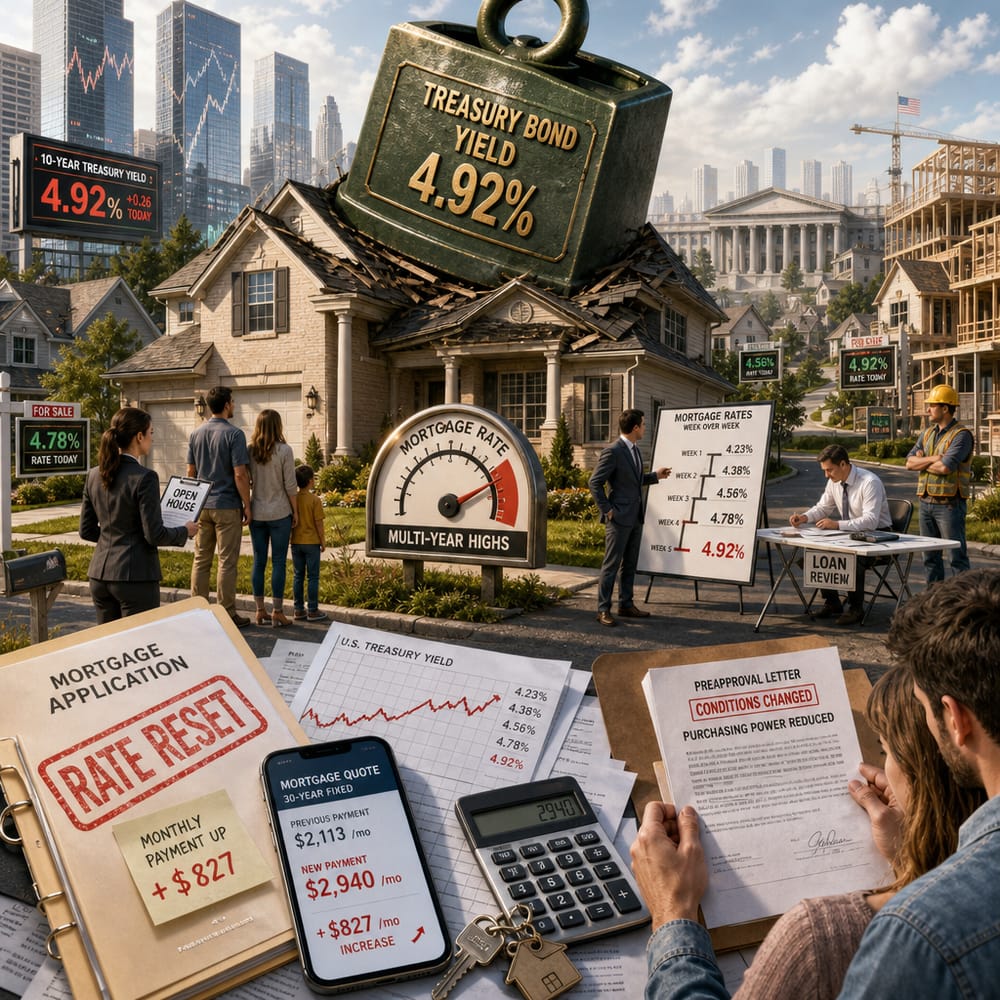
MORTGAGE RATES CLIMB TO MULTI-YEAR HIGHS AS BOND YIELDS REMAIN ELEVATED
Hold on to your hats, homebuyers, because the mortgage rollercoaster is cranking up the “thrill” level again. Mortgage rates have just hit their highest levels since the days when TikTok dances were all the rage — July 2025, to be precise. And guess what? We’ve got elevated bond yields to thank for this wild ride.
So, what's cooking with these stubbornly high mortgage rates? It all boils down to the Treasury yields — those somewhat dull but essential workhorses of the financial world. When these yields rise, mortgage rates often follow suit like a loyal puppy, because lenders want to ensure they are compensated for the risk of lending money over a long period. Think of it as the financial world's version of "if you scratch my back, I’ll scratch yours."
Prospective homeowners, on the other hand, might feel like they're caught in a financial tug-of-war. Higher mortgage rates can feel like a slap in the face, especially when you're trying to snag that dream home without needing a GoFundMe campaign. For the average first-time buyer, these rate hikes can translate into increased monthly payments that stretch budgets thinner than a paper napkin at a barbecue.
So, how does this reality check affect the broader housing market? In a word: affordability. With the cost of borrowing climbing up, fewer people can afford to dive into the housing market. This stumbling block might cool down the red-hot real estate scene we've seen in recent years. Remember those intense bidding wars where homes sold faster than concert tickets? With rates heading north, some of that frenzy might simmer down.
But let's not kid ourselves; the ripple effects of these rate hikes go beyond just sticker shock. When borrowing costs rise, it tends to slow down the housing market, which could lead to fewer home sales. And when that happens, it affects everyone from real estate agents to the local hardware store relying on new homeowners sprucing up their places.
As if buying a house wasn't already complicated enough, now prospective buyers need to factor in these rocketing mortgage rates. It might even lead some folks to decide to stick with renting just a little bit longer, joining the millions of Americans who are rolling their eyes at the property ladder from afar.
To add a dash of optimism, if you're already saddled with a mortgage, the silver lining is that rising rates could mean your home's value might stabilize, instead of ballooning to unsustainable levels. A more stable market could prevent future homeowners from finding themselves stuck with a property that’s worth less than what they paid.
The rising rate phenomenon also isn't happening in a vacuum. As the Federal Reserve continues its tango with inflation, aiming to keep it in check, these rate movements are part of a broader dance. The interplay between Federal Reserve policies and market reactions is more choreographed than a Broadway musical, though often much less entertaining for anyone trying to budget.
So, what should you, the savvy reader, do in this financial landscape? If you're in the market for a home, it might be time to get cozy with a financial advisor. They can help sift through the noise and find a strategy that doesn't involve living in your in-laws' basement. For those who already have a mortgage, it might be time to sit tight and enjoy the ride, or maybe explore refinancing options if the rates eventually dip.
In the meantime, keep your eyes peeled and your financial wits about you. The housing market is nothing if not unpredictable, a reality show where the prize is a permanent roof over your head. As rates continue to climb, remember that knowledge is your best tool. Stay informed, stay prepared, and maybe — just maybe — keep a bottle of celebratory champagne tucked away for when the perfect opportunity comes knocking.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.