

July CPI: Inflation Eases Slightly, But Shelter Still Hurts Core Outlook
Saturday, August 15, 2026
JULY CPI: INFLATION EASES SLIGHTLY, BUT SHELTER STILL HURTS CORE OUTLOOK
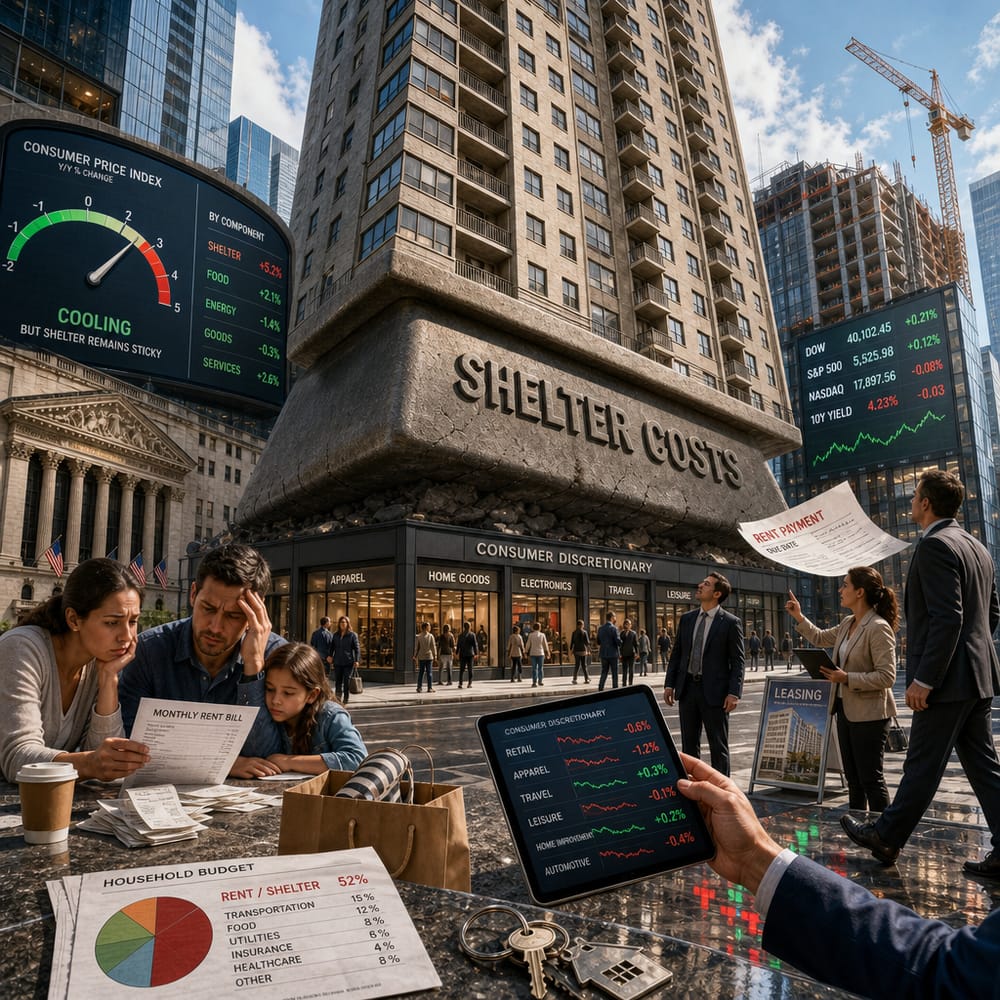
Inflation is like that pesky stain on your favorite shirt; just when you think you've finally gotten rid of it, it somehow manages to sneak its way back. The Consumer Price Index (CPI) for July tells a slightly optimistic tale on the surface: inflation is easing ever so gently. But dig a little deeper, and you’ll find the story isn’t all sunshine and rainbows. The shelter costs are stubbornly sticking around and keeping core inflation under pressure, making us all wonder what the Federal Reserve has up its sleeve.
WHY SHELTER COSTS WON'T QUIT
Let’s talk about that shelter cost, shall we? Think of it as that guest who overstays their welcome at a party. Just when you think they might be headed for the door, they grab another drink. The July CPI report reveals that while the inflation rate has cooled slightly, the shelter category continues to be a major driver of core inflation—which strips out the volatile food and energy sectors for a clearer view.
A big factor here is the ongoing housing market frenzy. Even though the broader inflation picture seems to be getting a touch rosier, shelter costs don't seem to have received the memo. With home prices and rents shooting up, particularly in tech-heavy cities like San Francisco, people are feeling the pinch in their wallets. The AI boom is throwing more fuel on this fire, with cash-rich tech workers bidding up prices and landlords feeling pretty smug.
THE FEDERAL RESERVE'S BALANCING ACT
All eyes are now on the Federal Reserve. The big question: How will it respond to the persistent inflation in shelter costs? The Fed's toolkit is not that of a magician's; it can't just conjure cheaper rent and houses, but it does have interest rates and monetary policy as its wands of choice. With shelter costs applying pressure, the Fed might consider keeping interest rates elevated longer than some would like. Higher borrowing costs could dampen housing demand, but if they're too high for too long, it could also chill the broader economy.
The Fed’s decision could ripple through the market like a stone skipping across a pond. If they decide to keep those rates high, borrowing will become pricier, potentially slowing consumer spending—the lifeblood of the economy. On the flip side, letting rates fall too soon could unleash the inflation beast once again. It’s a tightrope walk over a fiery pit of economic uncertainty.
WHAT'S NEXT FOR CONSUMERS AND MARKETS?
So, what are the implications for you and the broader market? For starters, if you're looking at real estate investments or consumer discretionary stocks—think of the stuff people buy when they have a little extra cash, like that vacation you’ve been dreaming of—it might be time to put on your analytical cap.
The real estate sector, influenced by the likes of Greg Abel’s acquisition of Taylor Morrison, paints a bullish long-term picture. But when you zoom in, the shelter cost inflation could make real estate a bumpy ride in the short term. Keep an eye on ETFs like the State Street SPDR S&P Homebuilders ETF (ticker: XHB). Although it hasn’t been the star performer historically, any hint of a housing market rebound could make it worth watching.
On the consumer spending side, July’s retail numbers were less than stellar. People are tightening their belts, and that’s a red flag for the consumer discretionary sector. Wary investors may want to tread carefully here, as consumer mood and spending habits can swing stocks like a pendulum.
BOTTOM LINE
To sum it up: while inflation has shown us a little mercy, the stubborn staying power of shelter costs keeps the outlook from being entirely rosy. The Fed is left juggling the dual mandate of keeping inflation in check while not stalling economic growth. And as for you, the retail investor, a keen eye on the Fed's moves and consumer behavior will be your guiding star through this maze of market unpredictability.
So, as you sip your morning coffee and scroll through your investments, remember: in the world of finance, the only constant is change. Stay curious, stay informed, and maybe keep a stress ball handy—just in case.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.