

JPMorgan Upgrades Bloomin’ Brands—Turnaround Play in Restaurants
Wednesday, September 30, 2026
IS BLOOMIN’ BRANDS FINALLY BLOOMIN’? JPMORGAN THINKS SO!
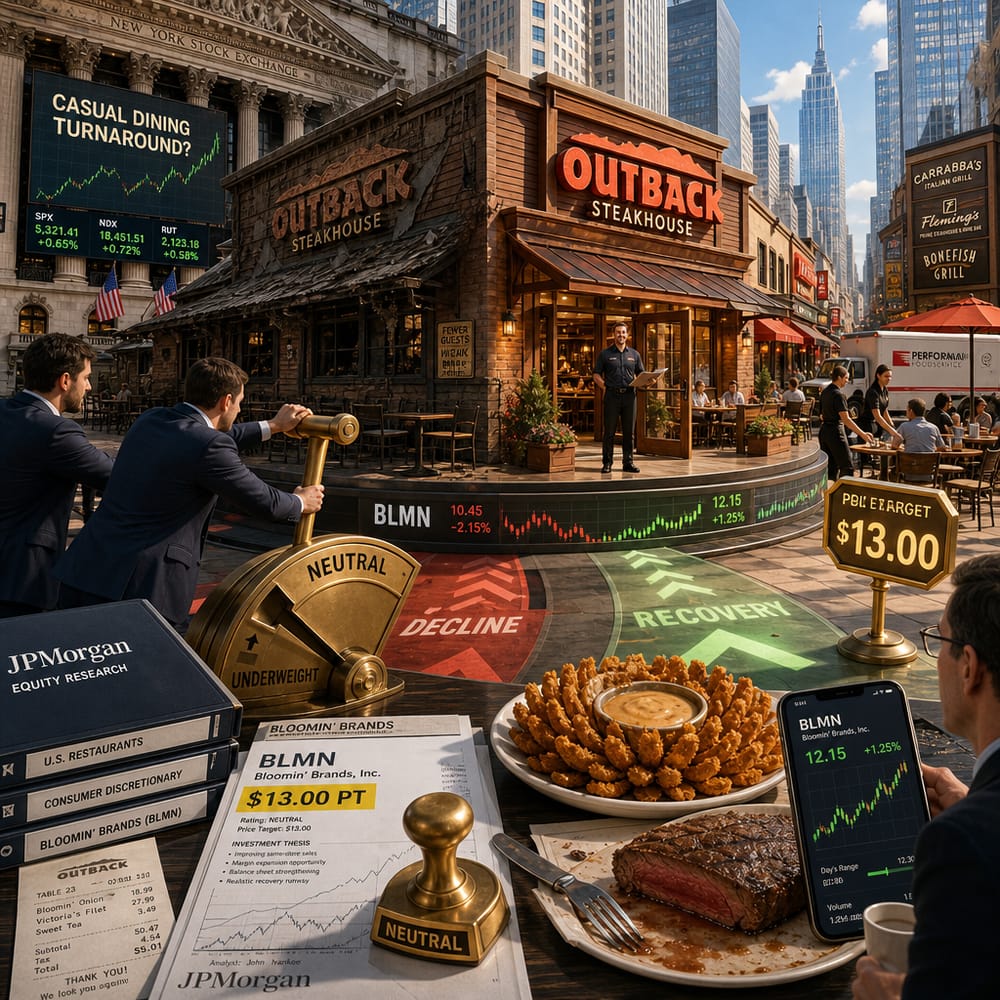
If Bloomin’ Brands were a steak on the Outback Steakhouse grill, it's been cooking a little too long on the "underweight" side. But wait! JPMorgan just flipped it over, raising its outlook from Underweight to Neutral, and bumping up the price target to a juicy $13.00. Could this mean the steaks—or rather, stakes—are getting higher for the casual dining sector?
First things first, let's address the big question: Why is JPMorgan suddenly sweet on Bloomin’ Brands, the parent company of Aussie-themed Outback Steakhouse? This upgrade isn't just a random act of kindness; it's a signal that some financial clouds might be parting. Easing cost pressures have created a more favorable climate for the casual dining industry, following a period when inflation was carving into profit margins like an overzealous maître d’.
The Federal Reserve's latest inflation report is music to the ears of restaurant chains. With core inflation hitting 3%, lower than the anticipated 3.7%, it gives the restaurant industry some breathing room. It’s like finding out there's a special on lobster tails right when you're cashing out. If costs are stabilizing, it means Bloomin’ Brands and peers might finally be able to serve up growth with a side of optimism.
Bloomin’ Brands’ performance compared to its peers has been like a roller-coaster ride on the Queensland Gold Coast. While Outback Steakhouse and Carrabba’s Italian Grill have tried to keep diners in their seats, rivals like Darden Restaurants (owner of Olive Garden) have been setting the table with better returns. Yet, here comes JPMorgan, suggesting Bloomin’ Brands may no longer be the shrimp on the barbie of the casual dining world.
What potential does Bloomin’ Brands have to dish out a successful turnaround? Well, if they play this right, they could benefit from improved consumer sentiment as inflation fears ease. People might feel more confident splurging on a Bloomin’ Onion (ever think you’d hear "onion" and "splurge" in the same sentence?) or two. Moreover, the brand's emphasis on off-premise dining, like takeout and delivery, could continue catering to post-pandemic preferences.
But don’t hang the 'Mission Accomplished' banner just yet. Bloomin’ Brands isn’t out of the woods. The casual dining sector faces challenges beyond inflation. Labor costs remain high, and the industry's need to keep attracting customers with competitive promotions and discounts isn’t going away anytime soon. Plus, consumer spending habits are as unpredictable as a kangaroo on caffeine, with trends veering towards experiences and value.
Another hurdle? The looming shadow of a labor market that, while stabilizing, is still sending mixed signals. According to ADP, private sector jobs rose by 90,000 in September, a figure that, while encouraging, underscores the uneven nature of the recovery. If job growth falters, consumers might tighten their belts faster than you can say "endless breadsticks."
Investors, if you're eyeing Bloomin’ Brands as a potential ticket to profits, consider this: JPMorgan's upgrade to Neutral isn't a ringing endorsement, but rather a cautious nod that things might not be as grim as they once seemed. It’s not quite the time to go all-in like a high roller at a Vegas casino buffet, but it might be worth a nibble if you believe in the broader recovery narrative in casual dining.
So, will Bloomin’ Brands rise like a soufflé or flop like a day-old pancake? It all boils down to how effectively the company can navigate these choppy waters and capitalize on a slightly sunnier economic outlook. Keep an eye on cost management, customer loyalty initiatives, and competitive positioning—all crucial elements that could determine whether Bloomin’ Brands becomes the talk of the town or stays an also-ran in the restaurant realm.
Until then, investors, put down your forks and knives, keep your napkins handy, and watch closely as Bloomin’ Brands tries to cook up a comeback worthy of your portfolio.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.