

Inflation Eases Slightly in July, But Core Pressures Remain
Tuesday, August 18, 2026
INFLATION EASES SLIGHTLY IN JULY, BUT CORE PRESSURES REMAIN
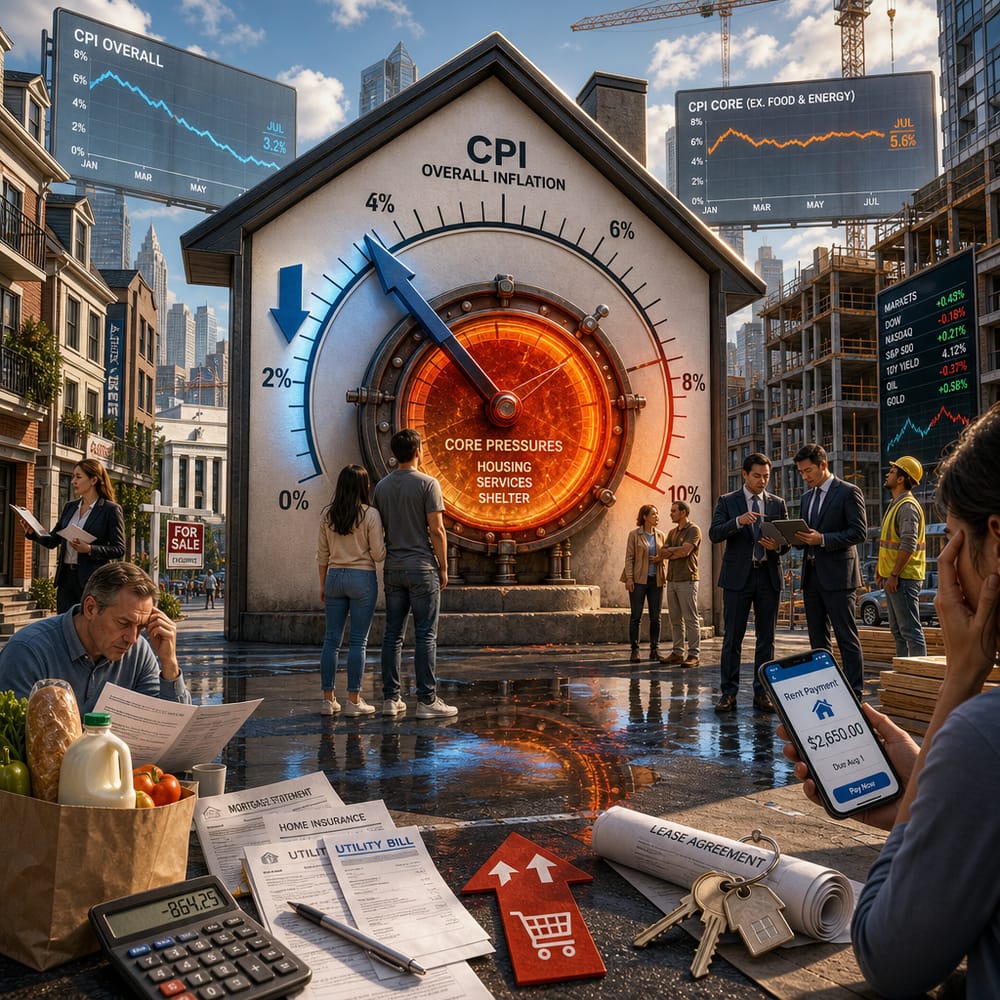
Hold onto your hats, folks, because while July’s Consumer Price Index (CPI) might whisper sweet nothings of easing inflation, the core issues are still lurking like uninvited guests at a wedding. Think of it as finally spotting a sunny day in Seattle—nice, sure, but don’t stash away that umbrella just yet. The CPI showed a slight dip, but the persistent core pressures are playing a tricky game, particularly with housing leading the charge like it’s auditioning for a starring role in “Keeping Up with Inflation.”
So, where is this core inflation coming from? Picture the economy like a house party. You’ve got the usual suspects having a good time: food, energy, and even the guy who always brings the veggie platter. But then there’s housing, the life of the party who just won't leave. Rent prices are like that persistent tune stuck in your head—no matter how hard you try, it’s here to stay. Housing is contributing significantly to core inflation, overshadowing the cheerful tunes of moderation in other sectors.
Now, let’s talk about the Federal Reserve, the monetary maestro trying to conduct this chaotic symphony. You might be wondering how the Fed will respond to this persisting core inflation. Imagine the Fed as a tightrope walker, balancing between reining in inflation and not toppling the economy into a recession. With core inflation refusing to take a back seat, the Fed may have to keep interest rates higher for longer. It’s like trying to calm a hyperactive puppy with stern commands when treats aren’t doing the trick.
But what does this mean for you, the everyday investor scrolling through your phone? Well, it’s a bit of a double-edged sword. On one hand, if the Fed decides to maintain higher interest rates to curb inflation, borrowing costs will rise. That means higher rates on mortgages, loans, and credit cards—all of which feels like a nostalgic throwback to harsher economic times. On the other hand, if they manage to bring inflation under control, the purchasing power of your wallet might just breathe a sigh of relief.
It’s a tough dance. Higher interest rates can stifle economic growth, but the Fed’s primary gig is to keep inflation in check. Like a seasoned DJ, they need to read the room—too much bass, and they risk emptying the dance floor.
So, what’s the play for investors amid this inflation drama? Keep an eye on sectors like housing that are driving core inflation. If you’re in the market for a home, brace yourself for a bumpy ride, as housing costs remain a major player in the inflation story. Meanwhile, consumer sectors that could benefit from a potential downturn in inflation, such as tech or even some consumer goods, might be worth a gander. They stand to gain if inflation finally bows out of the spotlight.
As for consumer purchasing power, it’s a bit of a waiting game. Continued core inflation means that the everyday dollar might not stretch as far as it used to. But hey, with a little savvy budgeting and some strategic financial moves, you can still make the most of your hard-earned cash.
In a nutshell, the CPI report card for July might have passed the test, but it’s not valedictorian material just yet. Core inflation, led by housing, is the persistent itch that just won’t quit, and the Fed is left to figure out how to scratch it without causing a rash. So, while inflation takes its sweet time deciding whether to exit stage left, stay informed, stay strategic, and don’t let the financial headlines steal your sunny disposition.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.