

Fed Faces Growing Pressure: Will December Deliver a Half-Point Shock?
Friday, November 20, 2026
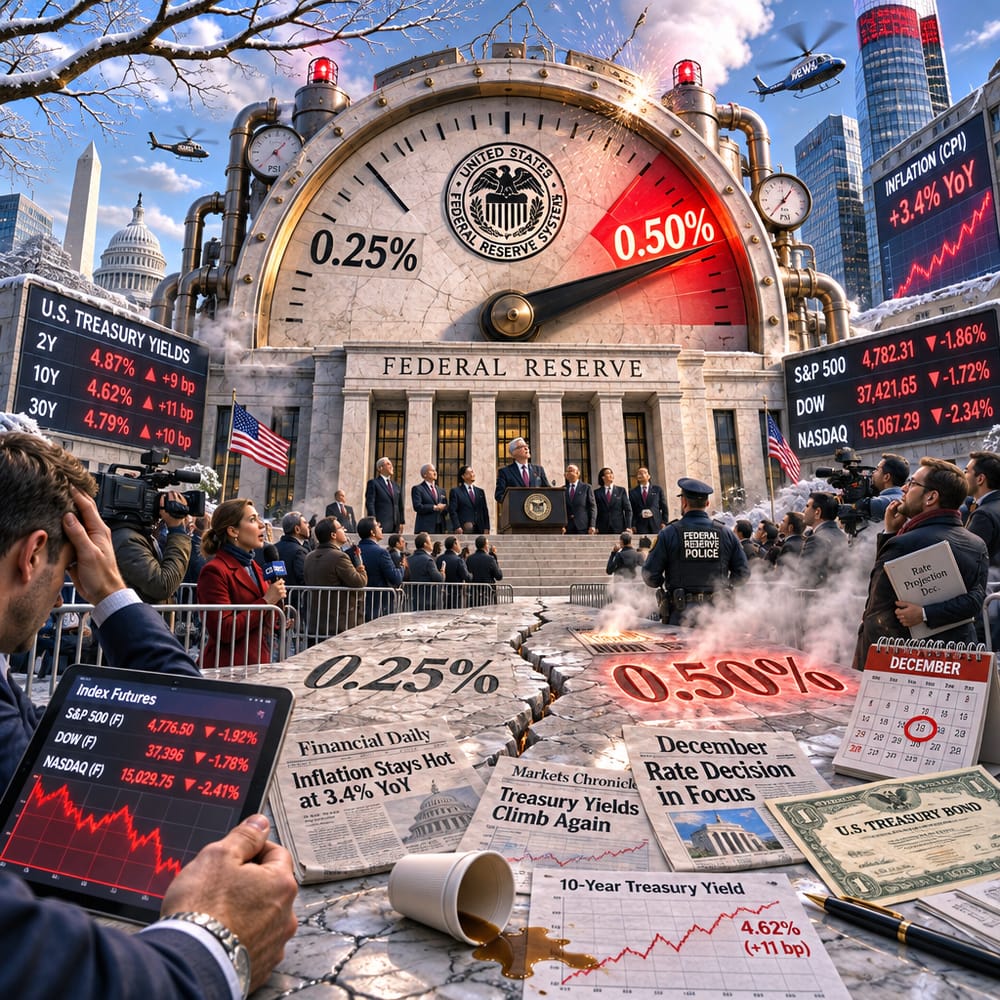
FED FACES GROWING PRESSURE: WILL DECEMBER DELIVER A HALF-POINT SHOCK?
Picture this: the Federal Reserve is like the nation’s designated driver on a night out. They've been nursing a ginger ale while the economy's been partying hard, fueled by low rates and easy money. But now, there's a sobering decision on the horizon. Will the Fed continue to gently tap the brakes with a 0.25% interest rate hike, or slam them with a more assertive 0.50%?
The December meeting is looming like a cliffhanger in your favorite TV drama, and the stakes are high. Inflation is the party crasher that just won't leave, raising the question: how aggressive does the Fed need to be to usher it out?
THE ARGUMENT FOR A HALF-POINT HIKE
Advocates for a 0.50% hike have a case grounded in urgency. Inflation is like a bad stain on the economy's favorite shirt—it needs strong detergent, not just a little warm water. Higher interest rates could be the bleach that prevents inflation from setting in too deep. Proponents argue that a bold move now might prevent more drastic measures later.
Economic conditions add fuel to their argument. Consumer prices have been stubbornly high, and while the tech sector is going through its own melodrama—hello, AI stock sell-offs—other sectors aren't immune to price pressures. Advocates say the Fed needs to act decisively to restore price stability, even if it means shaking up borrowing costs a bit more than usual.
THE CASE FOR CAUTION
On the flip side, some Fed members favor a more conservative 0.25% hike. They argue that the economy is a delicate soufflé right now, and one wrong move could see it collapse. With key stock indices like the Dow diligently descending into correction territory, there's a fear that overzealous rate hikes could stir the pot, sending markets into a tailspin.
And it's not just about the markets. Consumers, those everyday heroes keeping the economic engine running, would feel the pressure too. Higher interest rates mean higher costs for everything from mortgages to car loans. Tightening the screws too much could put a damper on consumer spending, just as we head into the holiday season—a crucial time for retailers trying to recoup a year of fluctuating fortunes.
MARKET REACTIONS AND RIPPLE EFFECTS
So, how might markets react if the Fed opts for the aggressive route? Picture a cat walking along the edge of a bathtub—things could get dicey. A 0.50% hike could cause a jittery reaction in financial markets, much like we’ve seen with the recent pullback in tech stocks. The Nasdaq’s been taking hits, with big names like Anthropic feeling the burn of their IPO flameout and pulling the rest of the tech sector along for the bumpy ride.
Bonds, too, would likely respond with U.S. Treasury yields spiking, reflecting the higher interest rates. This could be particularly tough on sectors reliant on cheap credit, like real estate and consumer goods. A rapid increase in borrowing costs could chill expansion plans or dampen consumer enthusiasm for big-ticket purchases.
THE CONSUMER IMPACT
For the average Joe and Jane, a larger hike would likely mean rethinking budgets. Mortgage rates, which took a breather earlier this year, would be primed for another climb. This isn't just about the price of a new home, but refinancing and home equity loans could become more expensive, too, putting a squeeze on disposable income just when families might be planning their holiday spending.
But it's not all doom and gloom. A more aggressive interest rate might finally help bring inflation into check, preserving the purchasing power of hard-earned dollars. After all, taming inflation is like cutting back on sugar—it’s tough in the short run but crucial for long-term health.
IN THE FED WE TRUST?
Ultimately, the Fed's December decision will likely be a balancing act worthy of Cirque du Soleil. Chair Jerome Powell and his fellow policymakers are under pressure to show they're serious about inflation without setting off panic alarms in the broader economy. Whether they choose a cautious path or a bold step forward, the implications will ripple through every corner of the financial world.
As the economy clinks its glasses of ginger ale this holiday season, all eyes will be on the Fed. Will they choose to dance with the devil they know—a small rate hike—or take the plunge with a bolder move? Whatever happens, it's bound to be a fascinating spectacle. Stay tuned, because this financial soap opera is far from over.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.