

Energy Sector Rotation: BP's Upgrade vs. Exxon's Downgrade
Monday, October 05, 2026
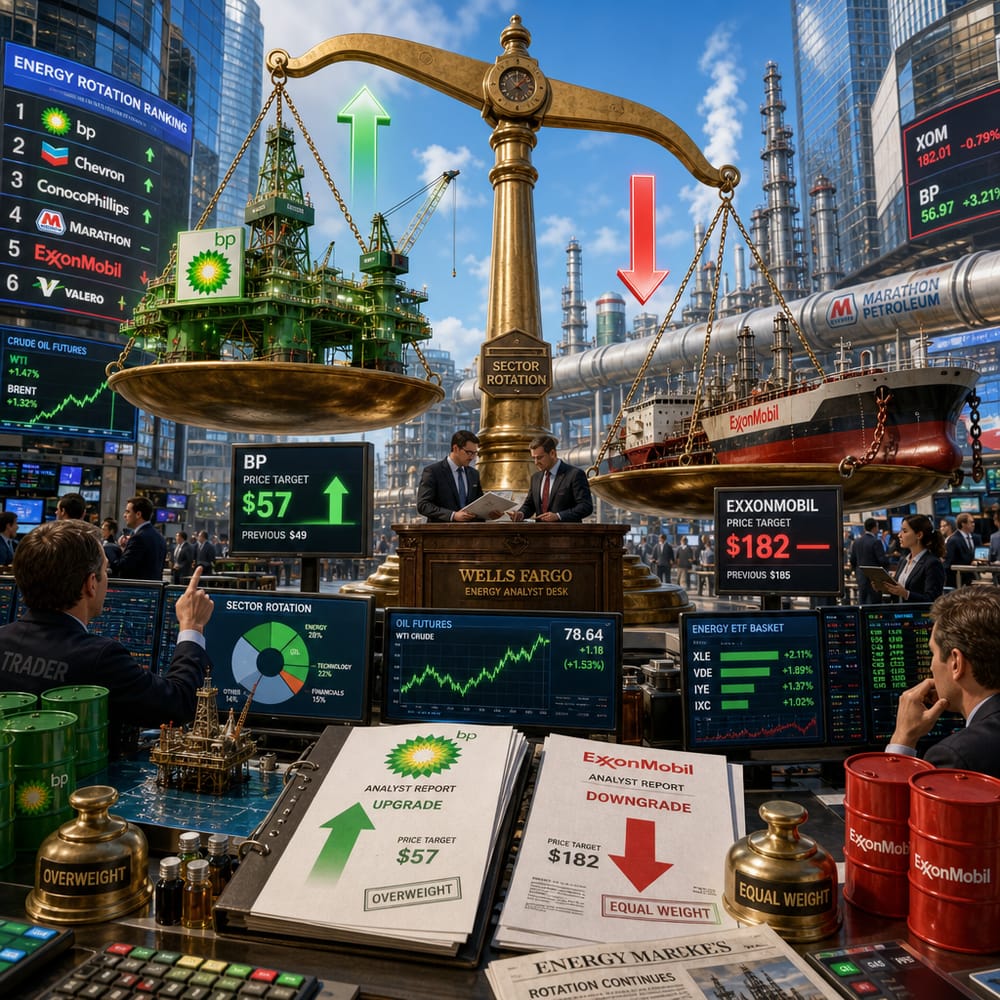
ENERGY SECTOR ROTATION: BP'S UPGRADE VS. EXXON'S DOWNGRADE
Blink and you might have missed it, but Wells Fargo just performed a financial quickstep that’s got energy investors talking. They’ve put BP on the dance card with a favorable nod, upgrading it to "Overweight," while ExxonMobil finds itself sliding down a notch to "Equal Weight." The numbers are out there: Wells Fargo has eyes on a $57 target for BP, while peering at a $182 target for Exxon. Grab some popcorn, because this energy sector soap opera is just getting started.
What’s the buzz about BP? Think of it as the comeback kid of the energy sector. Wells Fargo likes BP’s style, and it's easy to see why. The company's debt profile could make even the most stoic investor crack a smile. BP’s balance sheet is on a diet, shedding excess baggage and making room for leaner, meaner operations. It's like watching your favorite actor transform from a bit part to a leading role — everyone loves an underdog story.
Then there's ExxonMobil, the stalwart giant that usually doesn't need an introduction. But this fine day, it's taking a bit of a breather. Despite its heavyweight status, ExxonMobil is now just "Equal Weight" in Wells Fargo’s eyes. It's still a big deal — you don’t just ignore a company with a market cap that could rival a small country’s GDP — but the bloom is off the rose, for now at least.
But why this sudden change of favor? Simple: valuation and strategy. BP appears undervalued, a diamond in the rough, with promising future prospects that could make your uncle's dusty ExxonMobil shares look a tad less appealing. The rotation signals a strategic shift, with analysts betting on those who are innovating and evolving, not just maintaining the status quo.
For retail investors flipping through this with morning coffee — this sector rotation isn't just Wall Street drama. It's a heads-up that your portfolio could use a check-up. The energy sector is dancing to a new beat, and staying in step means understanding who’s leading the dance and why.
How does this affect the larger picture for energy investors? Well, it could be time to stop chasing the usual suspects and look beyond U.S. borders. BP’s newfound favor speaks to broader valuation differences between U.K. and U.S. energy companies. The Brits might just be onto something with their valuation metrics, which tend to mirror their famous reserved demeanor — less hype, more substance.
The implications for sector allocations are significant. Investors might start to shift their gaze towards more undervalued stocks with better debt profiles, potentially shaking up traditional energy portfolios that have leaned heavily on American behemoths like ExxonMobil.
But don’t write off the U.S. energy giants just yet. Marathon Petroleum, another player in the field, is an example of a U.S. company with a compelling story and strong future prospects. Though it didn’t get the spotlight in this particular Wells Fargo shuffle, keep your eyes peeled — the energy sector is nothing if not a stage for surprises.
In the end, whether you’re a rising star like BP or a stalwart like ExxonMobil, the dance of market favor can change in a heartbeat. For savvy investors, the key takeaway is to stay nimble and keep your ear to the ground — or in this case, to the pipeline. After all, in the world of energy investing, fortune favors those who are ready to pivot and adapt, just like Wells Fargo did with this latest sector shuffle.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.