

Credit and Mortgage Rates Remain Elevated — No Relief Yet
Monday, August 10, 2026
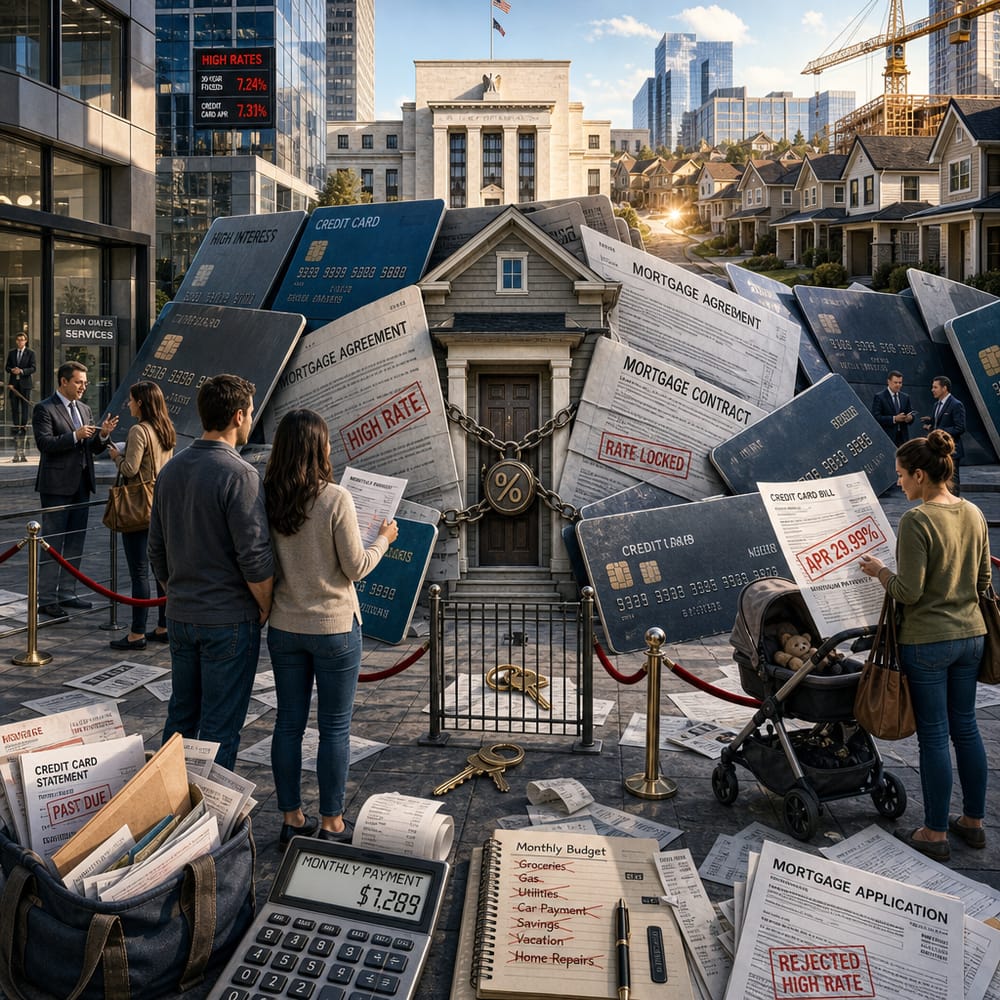
CREDIT AND MORTGAGE RATES LINGER AT LOFTY HEIGHTS — NO RELIEF IN SIGHT
If you've been waiting for a break in credit card or mortgage rates, you might want to get comfortable. Despite the Federal Reserve’s decision to hit the pause button on interest rate hikes, borrowing costs are treating that news like it’s yesterday’s leftovers. High rates remain the stubborn guest that won’t leave the party, and consumers are feeling the pinch.
Let’s dive into the why. The Fed has held steady, but it’s not enough to send lending rates tumbling back to earth. Market forces, like the Treasury yields and inflation expectations, are playing a game of tug-of-war, keeping credit costs high. The 10-year Treasury yield, a key influencer of mortgage rates, barely budged and sits around 4.666%. It's like watching paint dry.
So, why are credit card and mortgage rates giving us the cold shoulder? Blame the inflation bug. Investors are jittery, and they're demanding higher yields for long-term loans. This cautious stance is a little like always carrying an umbrella in case of sudden rain — you never know when inflation might sneak back up.
Now, let’s talk about how consumers are dealing with these elevated borrowing costs. Picture this: juggling flaming torches while riding a unicycle. Okay, maybe it’s not that dramatic, but families are certainly feeling a tightening squeeze on their wallets. With credit card interest rates feeling like a constant uphill battle, households are strategizing on how to avoid getting scorched. Many are opting to reduce their credit card balances, prioritize essential purchases, and hunt for better rates like modern-day financial warriors.
In the housing market, the story reads similarly. Homebuyers, who hoped for a breather, are tightening their belts as mortgage rates hover near the stratosphere. The dream of a white picket fence is facing delays as potential buyers grapple with monthly payments that feel more like paying for a second home, even if it’s the first.
The long-term effects on the housing market? Hold on to your hats. Elevated rates could dampen the fire under housing demand. Less borrowing means fewer people entering the homebuying game, potentially leading to a cooling market. Picture realtors twiddling their thumbs at open houses with not much more than the sound of crickets for company.
But let’s not forget the ripple effect. High borrowing costs can lead to reduced consumer spending. When people can’t spend freely, it puts a damper on economic growth. And, in economic terms, that’s like a heavyweight champion suddenly getting wobbly on their feet.
So, what’s next? If you're a consumer, it’s all about navigating these stormy seas. Keep an eye on inflation reports and the Fed’s next moves, because those will be the tea leaves to read in the coming months.
Meanwhile, as we wait for rates to cool down (a little like watching for a solar eclipse), it’s a good time to check those financial sails. Look for opportunities to refinance, pay down high-interest debt, and diversify income streams to weather this financial landscape.
In this game of interest rate limbo, it’s clear we’re not touching the floor just yet. But, like any savvy investor, it’s all about playing the long game, keeping a watchful eye, and holding steady until the winds shift in a more favorable direction. So sit tight, because the financial weather forecast still calls for gathering clouds — but there’s always a chance of a break in the rain.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.