

CPI Edges Down, Core Remains Sticky — Impact on Bond and Mortgage Markets
Tuesday, August 18, 2026
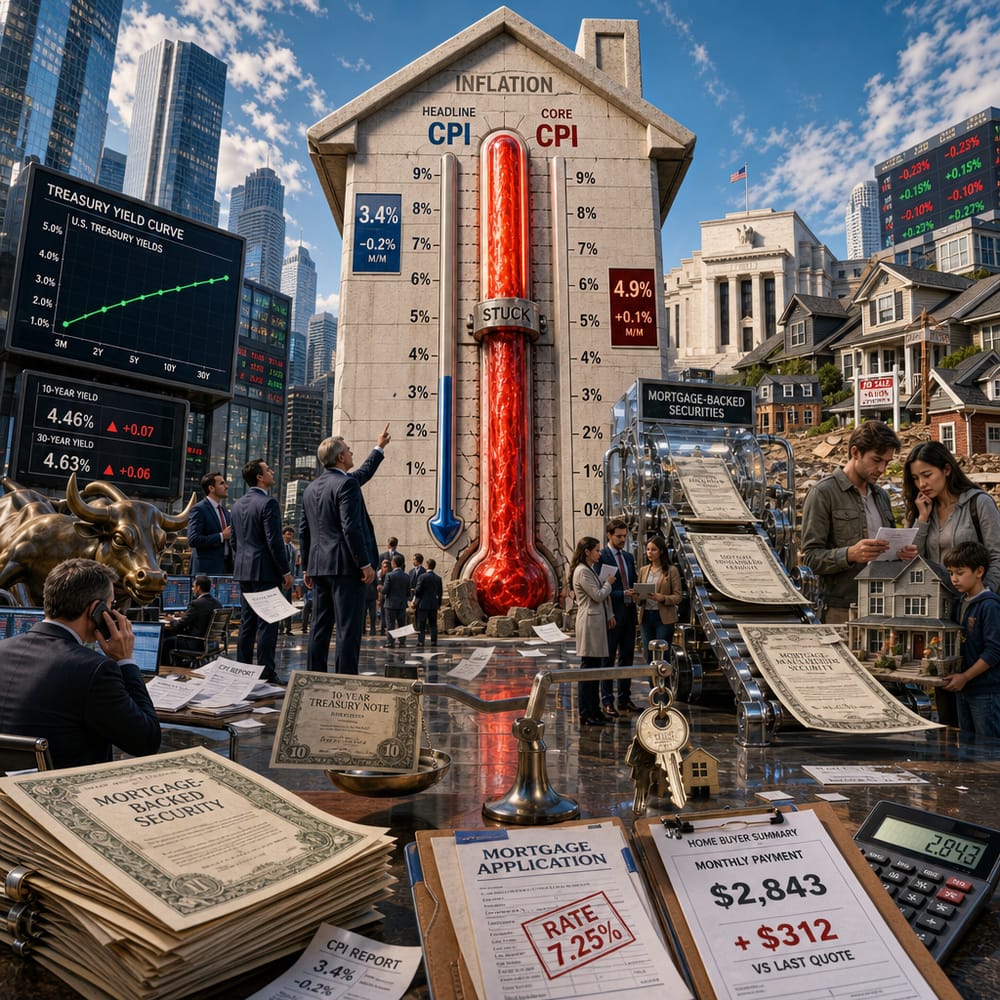
WHEN HEADLINE NUMBERS MASK A STICKY REALITY: CPI, TREASURIES, AND MORTGAGES
If inflation were a horror movie, you'd think the villain was finally done for—until it leaps back up, core CPI in hand, proving it's here to stick around. That's what's happening in the economic theater this month as the Consumer Price Index (CPI) plays its latest role. The headline CPI for July dropped a smidge, prompting a sigh of relief. But hold your applause. A peek behind the curtain reveals core CPI isn't budging. It's as if inflation’s understudy suddenly decided it wants the spotlight.
So why should this matter to you, chilling with your morning coffee and scrolling through the headlines? Because this inflation tango directly affects your borrowing costs, from the Treasury yields that underpin pretty much everything, to the mortgage rates that determine whether that dream house stays a dream or becomes your reality.
TREASURY YIELDS: THE BAROMETER OF BORROWING
When you think Treasury yields, imagine them as the mood ring of the financial world. They tell you how the market feels about inflation and fiscal policy. And right now, that mood ring is glowing an angry red. With 30-year Treasury yields scaling the dizzying heights of 5.33%, their highest in nearly two decades, it’s clear investors are wary. Why? The fiscal deficit is ballooning, and inflation feels like that uninvited guest at a party—it shows up early, stays late, and doesn’t take the hint to leave.
Here's the deal: Treasury yields and bond prices are like two kids on a see-saw—when one goes up, the other goes down. This inverse relationship matters because higher yields mean higher borrowing costs for the government, which can trickle down to you and me, affecting everything from car loans to the monthly mortgage check.
MORTGAGE MARKETS: SITTING IN THE BACKSEAT OF THE YIELD CAR
Now, let's steer this conversation into the realm of mortgages. If you’re clutching a mortgage application tighter than a VIP pass to a concert, you’re in for some turbulence. Mortgages are closely tied to Treasury yields. Specifically, the 10-year Treasury note, which is a key benchmark for these loans, has also seen its yield climbing.
Mortgage lenders take their cues from these yields. When Treasury yields are high, lenders hike mortgage rates to maintain their profit margins. It’s a classic case of the domino effect. With core inflation refusing to budge, the Fed remains hawkish—that's central-banker lingo for "we might keep raising interest rates"—which could lead to even more upward pressure on yields.
WHY THIS MATTERS TO AMERICAN HOUSEHOLDS
All this financial jargon boils down to one key point for everyday Americans: your wallet could feel thinner. As Treasury yields rise, expect to fork over more cash in interest whether you're buying a new home, taking out a loan, or just trying to keep your credit card debt in check.
This isn’t just a number on a page—it’s monthly payments, it’s credit card debt, it’s whether you can afford that extra room in your new place. With core CPI sticking around like that unwanted houseguest, the likelihood of yields and mortgage rates dropping soon looks as bleak as a weather forecast of endless rain.
The mortgage market, much like the bond market, will likely remain jittery. If you’re in the process of buying a home, this could mean more volatile mortgage rates, and for those with existing mortgages, the refinancing window might not be as open as you'd like.
THE UNPREDICTABLE PATH AHEAD
So, what should you take away from this financial saga? Prepare for a bumpy ride. Keep a close eye on Treasury yields, especially if you’re on the verge of a big purchase or investment. The CPI numbers give you a glimpse of economic pressures, but they're just pieces of a larger puzzle involving fiscal policy, global economics, and yes, even the state of negotiations—or non-negotiations—with nations like Iran, which can impact oil prices and, in turn, inflation.
As we digest these numbers, remember: in the rollercoaster world of finance, forewarned is forearmed. Whether you're a seasoned investor or just someone trying to make sense of the markets, keep your seatbelt fastened. While the headline numbers may hint at progress, it’s the sticky details where the real story unfolds.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.