

Cerebras Systems Raises Full-Year Guidance, Stock Slides 12%—Margin Worries in Spotlight
Wednesday, August 12, 2026
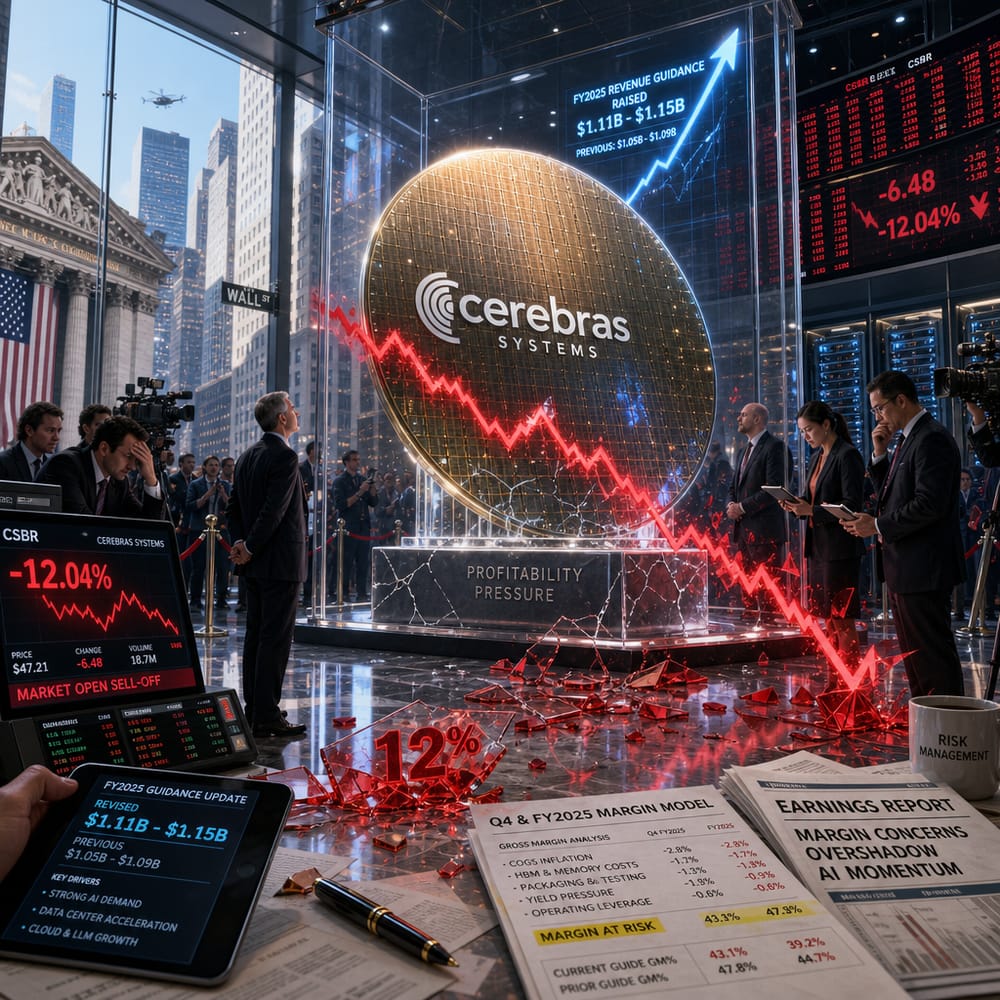
Cerebras Systems Raises Guidance, But Investors Say "Meh" To Margins
In the mercurial world of Wall Street, up doesn't always mean up. Case in point: Cerebras Systems. You'd think raising the full-year revenue outlook would send investors into a frenzy like kids in a candy store. But instead, the chipmaker’s stock nosedived a shocking 12%. Why the cold shoulder despite the warm forecast? The answer lies in investor anxieties over profitability — or the lack thereof.
WHAT'S EATING CEREBRAS?
Cerebras recently trumpeted an uplifting tune: they’re bumping up their full-year revenue expectations to between $880 and $890 million. That's an increase from the earlier $855 million to $865 million range. Great news, right? A symphony for shareholder ears? Not quite. While the revenue crescendo played out beautifully, investors immediately noticed the discordant note of margin worries.
In its second earnings report since debuting on the stock market stage, Cerebras posted a net loss of a staggering $450.5 million. That's quite the contrast from a profit of $309.5 million — or $1.91 per share — they recorded a year earlier. The company chalked up $180.1 million in GAAP revenue for Q2 but hemorrhaged cash in the pursuit of AI dominance.
THE MARGIN DILEMMA
Here’s the crux of the matter: Cerebras's cost of doing business is soaring, thanks largely to the AI arms race. The company is spending big to stay ahead of the pack with its cutting-edge AI chips, but this isn’t a cheap endeavor. The spending spree has eaten into their margins faster than a kid demolishing a bag of Halloween candy.
Investors are understandably nervous. They're asking pointed questions: Can Cerebras turn this ship around and bring profitability back on deck? Or is it destined to list under the weight of its own ambitions?
COMPARING NOTES IN THE AI SYMPHONY
Cerebras isn't in this orchestra alone. Its story mirrors much of what's happening across the AI infrastructure sector. Consider CoreWeave, a fellow AI player that recently saw its stock soar after revealing a whopping 112% increase in Q2 revenue. But even they aren't basking in limitless glory. Like Cerebras, CoreWeave isn't profitable yet. They’ve just managed to serenade investors with higher revenue and a bulging revenue backlog that promises future potential.
The broader AI market isn't short on demand - companies like Nvidia and its older chip models are still hot picks. The challenge lies in balancing today's significant costs with tomorrow's profitability. For Cerebras, maintaining this balance while keeping investors tuned in will be critical.
WHAT'S IN STORE FOR CEREBRAS?
The key question for Cerebras, and its shareholders, is how well the company can juggle growing revenues with declining margins. Investors are betting on whether the company can eventually convert its technological prowess into cold, hard cash. Until then, any revenue guidance that doesn't come with a cheerful profit margin may be met with a collective sigh.
The AI chip sector is one long chess game, and every loss or gain in valuation is a move that could set the stage for the next play. For now, it seems the market wants not just growth, but growth paired with a path to profitability. A tricky combination that will require management to channel its inner grandmaster.
In the world where chips are the new gold rush, Cerebras Systems has the tools to strike it rich. The big question is whether they can do it profitably before investors run out of patience. So, as investors mull over their spreadsheets, one could say Cerebras Systems is learning to dance on a high-wire — one misstep could mean a fall, but keep the rhythm, and they just might dazzle the crowd.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.