

Cerebras Systems: Navigating Growth Amid Profitability Concerns
Wednesday, August 12, 2026
Cerebras Systems: Navigating Growth Amid Profitability Concerns
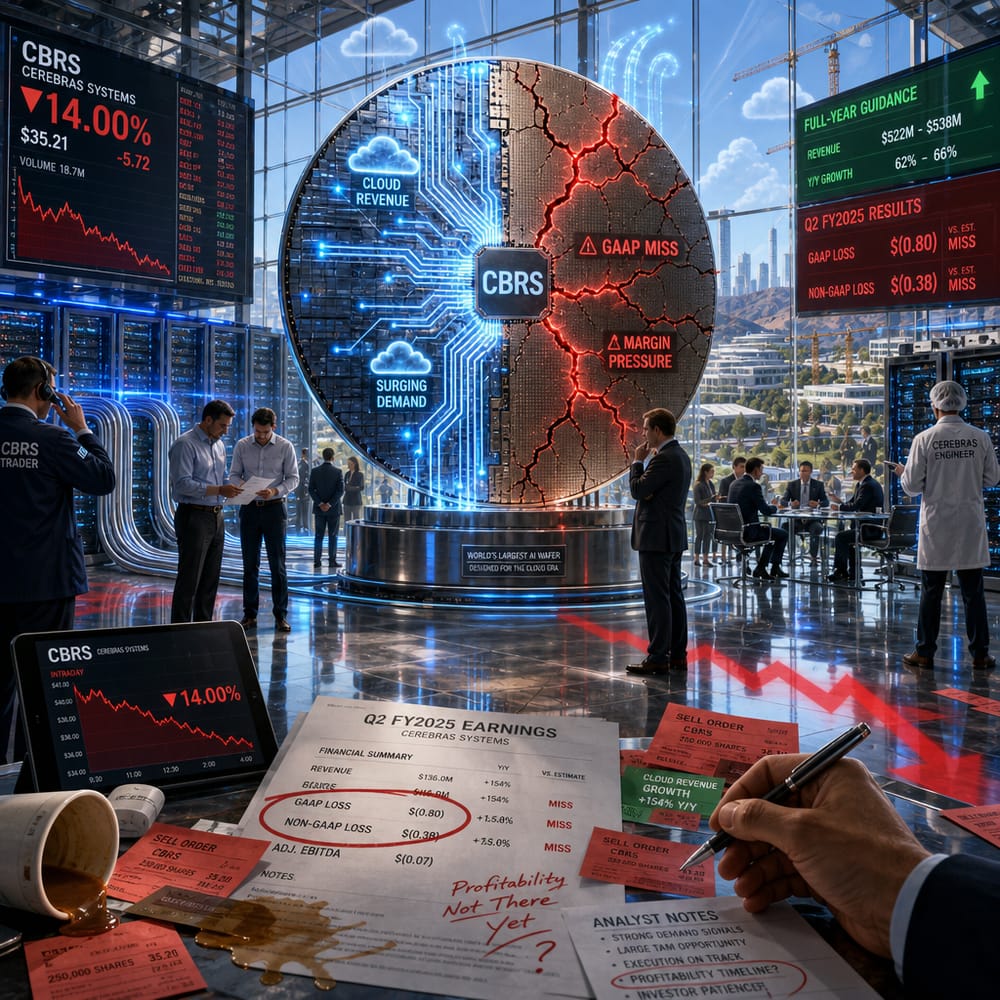
If drama were a stock, Cerebras Systems would be trading at an all-time high. Picture this: you just had a stellar quarter with cloud revenues looking like they drank a potion of growth hormones, only to watch your stock stumble a baffling 14% in after-hours trading. What's causing this Wall Street rollercoaster, and what does it mean for the future of this ambitious chipmaker?
Cerebras Systems, a key player in the AI and semiconductor arena, might have thought they were on cloud nine after reporting impressive growth in their cloud division. Instead, they got a rude awakening when investors showed they cared more about the bottom line than just rosy revenue numbers. Despite raising their full-year guidance—like a student confidently predicting straight A's after a decent report card—investors zeroed in on the less-than-stellar earnings and profitability woes.
Now, let’s get into the nitty-gritty. Cerebras’s cloud business is the rockstar here, and it's not just about nice hats and guitars. The demand for AI continues to skyrocket, and with it, the thirst for cloud solutions that can handle the computational heavy lifting. Cerebras seems well-poised to ride this wave, offering products that can crunch data faster than a supercomputer on caffeine. Their cloud division is growing robustly, proving they have their finger on the pulse of an ever-expanding market.
However, while the cloud business is the dazzling star of the show, profitability—or the lack thereof—is the gloomy understudy. The company reported a net loss of $450.5 million, a figure that would make any investor do a double-take. Most shockingly, this loss comes after a profitable stint just a year earlier. The elephant in the room? A mountain of stock-compensation costs that’s turning CFOs’ hair gray.
Investors aren’t just in this for the short-lived highs of cloud revenue spikes; they want sustainable profitability. This is where the shiny cloud narrative gets clouded by concerns over the hardware segment—an area that seems more like a draining battery than a Tesla supercharger. Hardware revenue is not just disappointing; it’s borderline alarming for those scrutinizing the grand revenue pie.
The hardware segment is crucial because, in a world driven by tech marvels, chips and hardware are your bread and butter. Right now, Cerebras’s hardware feels more like stale toast. For Cerebras to reclaim investor love, addressing these hardware shortfalls is non-negotiable. A strategic revamp could involve leveraging their AI prowess further or possibly diversifying their hardware offerings to capture more market segments.
So, what’s the playbook for Cerebras? For starters, they need to sweat the small stuff—trimming cost and enhancing manufacturing efficiency could turn those heavy losses into slimmer victories. Then, there’s the option to innovate their way out. Enhanced product lines or strategic partnerships in the tech ecosystem could turbocharge hardware sales.
Cerebras's boardroom should probably look like a bustling startup garage right now, full of ideas on how to convert cloud promise into real profits. Streamlining operations, entering new markets, and perhaps even restructuring their business model could be the key to transforming from an ambitious upstart to an industry heavyweight.
In this high-stakes game, the company must convince Wall Street that it’s not just about big ambitions, but about executing a strategy that delivers consistent returns. For retail investors keen on riding the AI wave, the question is whether Cerebras can balance its cloud growth with a financial strategy that doesn’t send investors reaching for the panic button.
As the dust settles, Cerebras’s journey remains one of high potential mixed with equally high risk. Its ability to navigate these choppy waters will determine whether it emerges as a darling of the tech world or just another company grappling with the weighty expectations of its IPO promises. For now, it’s a wait-and-see game, with investors eagerly scanning the horizon for signs of smoother sailing.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.