

Celestica's Earnings Paradox: Strong Results, Weak Stock
Thursday, August 06, 2026
CELESTICA'S EARNINGS PARADOX: STRONG RESULTS, WEAK STOCK
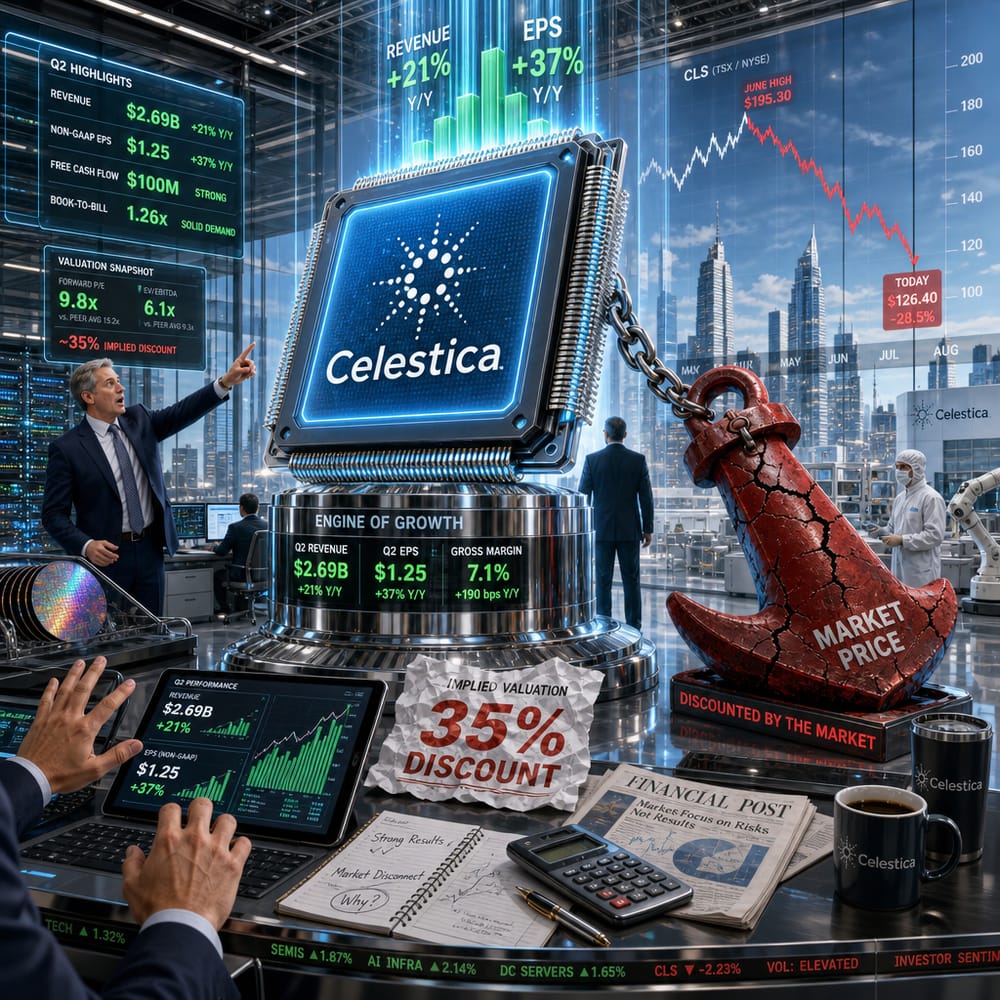
Welcome to the rollercoaster ride of Celestica, where impressive earnings meet a stock that clearly needs a pep talk. How can a company post knockout second-quarter results and still watch its stock take a dive? Grab your popcorn, because this financial thriller is one for the books.
Picture this: Celestica, a notable player in the semiconductor and hardware sector, struts into the earnings arena with revenue and earnings per share (EPS) growing faster than a viral TikTok dance. With such stellar performance, you'd expect investors to be partying like it's 1999. Yet, somehow, Celestica's stock is underappreciated, trading at a 35% discount from its June highs. It's like winning the lottery and then misplacing the ticket.
So, what's causing this earnings paradox? For starters, there's the matter of Celestica's customer base. While having loyal customers is usually a good thing, Celestica's are a bit too concentrated for comfort. If one big client decides to jump ship, it could be like pulling the wrong block from a Jenga tower—everything might come crashing down. This risk poses a significant concern for investors who prefer their bets less thrilling and more stable.
But wait, there's more to this mystery. Celestica has grand plans for a whopping $1–$1.5 billion capital expenditure (capex) spree, aimed at expanding its facilities by 2026. It’s a bold move designed to instill confidence and future-proof the company. Think of it as a way to beef up the company's muscles to flex even harder in the semiconductor space. But these days, investors need more than promises; they want to see concrete results and a guarantee that this hefty spending will indeed pay off.
Then there's the market's fickle nature to consider. Despite the company's strong guidance and raised outlook, investors are selling. It’s like dumping your date because they're too perfect. Market sentiment sometimes dances to its own tune, and right now, it's humming a skeptical melody for Celestica.
And let's not forget valuation concerns. Post-pullback, Celestica's stock is hovering around a forward earnings ratio of 30 times. For some investors, this is as enticing as a lukewarm cup of coffee. In a market where investors crave stocks that promise not just value but also explosive growth, this valuation might seem like a Cinderella slipper that doesn't quite fit.
So, is CLS stock reasonably valued at this juncture? That's the million-dollar question. With its current predicament, Celestica is like the underdog in a sports film, down but definitely not out. For the bold, this might be the perfect time to buy low, hoping for a triumph-worthy comeback. However, for the cautious crowd, it's a waiting game—seeing if Celestica can deliver on its expansion promises and spread its customer risk.
Now, whether Celestica's strategic maneuvers will woo back investors or fall flat remains to be seen. What's clear is that, in the unpredictable world of finance, even the strongest performers can find themselves underappreciated. It's a reminder that in investing, as in life, things aren't always as they appear.
So, for those watching from the sidelines or deep in the throes of decision-making, keep an eye on Celestica. This paradox of strong results yet a weak stock could flip the script at any moment. After all, every stock has its day, and Celestica's might just be around the corner.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.