

Bond Market Whiplash: Treasury Yields Soar on CPI Shock
Wednesday, November 11, 2026
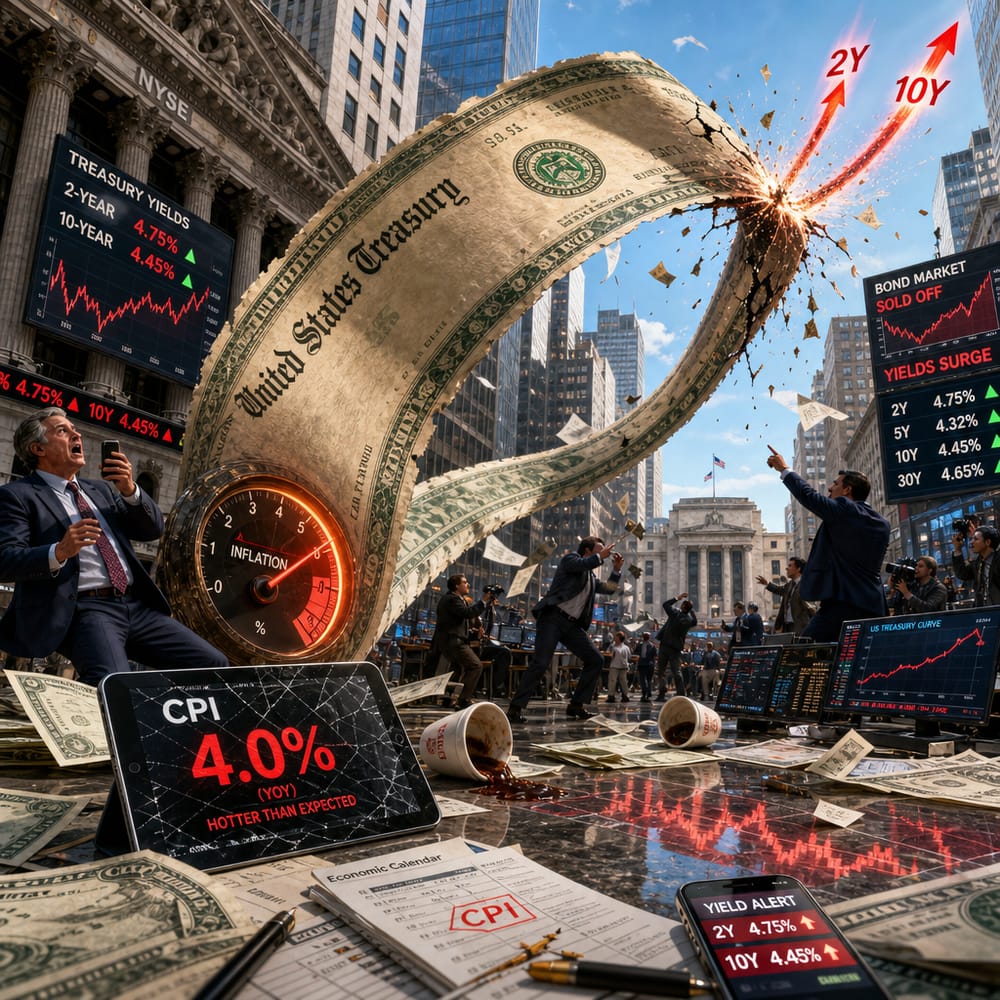
BOND MARKET WHIPLASH: TREASURY YIELDS SOAR ON CPI SHOCK
Brace yourselves, folks — the bond market just went on a wild ride, and the fallout could hit your wallet. Treasury yields have surged like an over-caffeinated runner since the latest Consumer Price Index (CPI) numbers hit the airwaves. Just a data sheet? More like an earthquake.
Here's the scoop: inflation reared its stubborn head again with a steeper-than-expected rise in consumer prices, prompting investors to bet that the Federal Reserve might roll out a parade of bigger rate hikes. Yes, that means the cost of borrowing money could shoot up like a New Year’s Eve firework.
So, what in the world does this mean for you, the savvy retail investor? Well, it’s not just numbers on a screen. When Treasury yields take a jog uphill, it’s a sign that investors are pricing in rate hikes, which are the Fed's tool to tame inflation by making borrowing more expensive.
TWO-YEAR AND 10-YEAR TREASURIES: WHY YOU SHOULD CARE
The two-year Treasury yield, typically a thermometer for Fed policy expectations, jumped 17 basis points — its heftiest single-day leap in 19 months. And the 10-year yield followed suit, bumping up as well. Think of these yields as the bread and butter of the bond market menu; they’re crucial indicators of what’s cooking in the economy.
Higher yields might sound like a win for bond investors — more return, right? But before you toast with champagne, remember that when yields go up, bond prices go down. That’s bad news for anyone already holding bonds. But wait, there’s more.
MORTGAGE AND BORROWING COSTS: THE RIPPLE EFFECT
The impact doesn’t stop at your bonds. When Treasury yields rise, it's like an echo chamber for other interest rates, including the ones that touch your daily life. Mortgage rates could edge higher, meaning that dream house might get a tad more expensive. Paying down student loans or credit card debt? Buckle up for potentially higher costs there too.
And let’s not forget about our corporate pals — higher borrowing costs for companies can squeeze their profit margins. This could weigh on their growth plans or share prices, especially for those knee-deep in debt. It’s like a harsh wind blowing against their sails just when they thought they were cruising.
LONG-TERM ECONOMIC IMPACTS: A CRYSTAL BALL VIEW
Zooming out, the implications of spiking yields are as complex as the latest binge-worthy Netflix drama. If the Fed’s rate hikes curb inflation successfully, it might usher in a stable economy down the road. But the journey there could be as turbulent as a rollercoaster in a hurricane.
For starters, aggressive rate hikes might curb business investment and consumer spending. Both are critical fuel for economic growth. If spending cools too much, we could be flirting with recession territory — a word no one likes to hear. So, the balance the Fed has to strike is trickier than walking a tightrope at 10,000 feet.
LOOKING AHEAD: YOUR ACTION PLAN
So, how do you navigate this bond market whiplash? If you’re holding bonds, especially long-term ones, you might see some red in your portfolio. But before you panic-sell, remember that bonds are often a steady hand during market storms. Consider diversifying with short-duration bonds if you’re worried about rising rates — they’re less sensitive to rate hikes.
On the equity side, keep an eye on sectors sensitive to interest rates, like real estate and utilities, which might feel the pinch more than nimble tech companies or those with strong cash positions.
In the end, staying informed and adaptable is your best bet. The bond market drama may be unsettling, but it doesn’t have to derail your financial goals. So, keep your wits about you, and maybe steer clear of the over-caffeinated runner for a bit.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.