

Bitcoin Miners Struggle Despite Record Prices and Trump’s Support
Friday, May 02, 2025
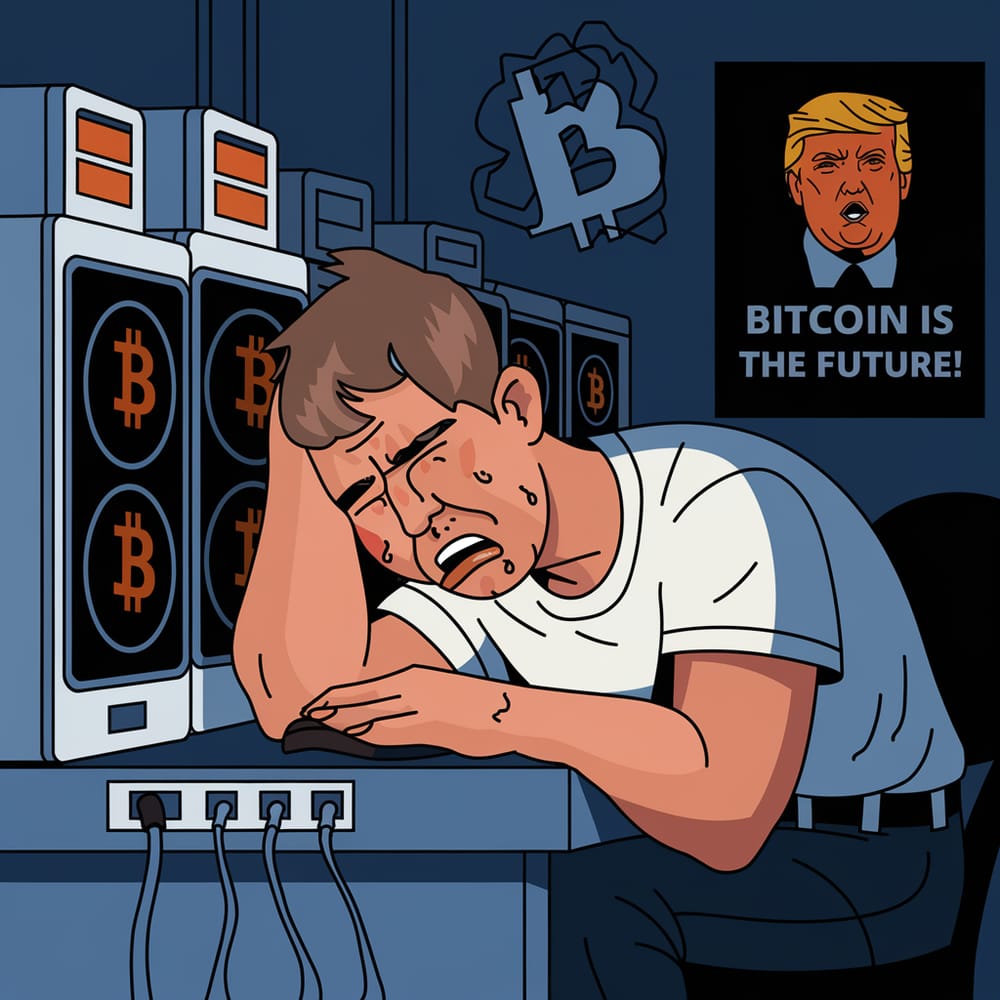
Bitcoin may be booming, but U.S. miners are hurting—and not even Trump’s pro-crypto policies can save them from a brutal first quarter.
Seven of the eight largest publicly traded Bitcoin mining companies in the U.S. are expected to post losses, with adjusted net income for the group plunging by $1.3 billion compared to last year. The big culprit? Rising competition, soaring energy costs, delayed shipments, and tariffs on mining rigs, many of which are imported from Asia.
Even though Bitcoin hit an all-time high above $109,000 in January, mining revenue didn’t keep up. Why? Hashrate difficulty exploded, meaning more computing power—and more cost—was needed to earn the same amount of BTC. Riot Platforms alone reported a $296 million loss, flipping from a $211 million profit last year.
Miners had ramped up purchases of expensive rigs in late 2024 when Trump’s election win sent crypto surging. But those rigs—often subject to tariffs and regulatory blacklisting—now weigh on profits as mining rewards continue shrinking.
The halving in April, which slashed Bitcoin rewards by 50%, didn’t help. Nor did the stock market volatility, which has made it tougher for these capital-hungry firms to raise money by issuing shares. Some, like CleanSpark and Riot, have turned to convertible debt and expanded credit lines to stay liquid.
The irony? Trump promised to make the U.S. a Bitcoin mining powerhouse, but his broader trade war has backfired—raising input costs and giving overseas competitors like Russia and China an edge.
Bottom line:
Bitcoin miners bet big on Trump and record prices—but tariffs, power costs, and global rivals are eating into profits. The crypto bull run hasn’t translated into mining gains—and Wall Street is watching closely.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.