

Align Technology's Price Target Slashed: A Valuation Warning
Monday, October 05, 2026
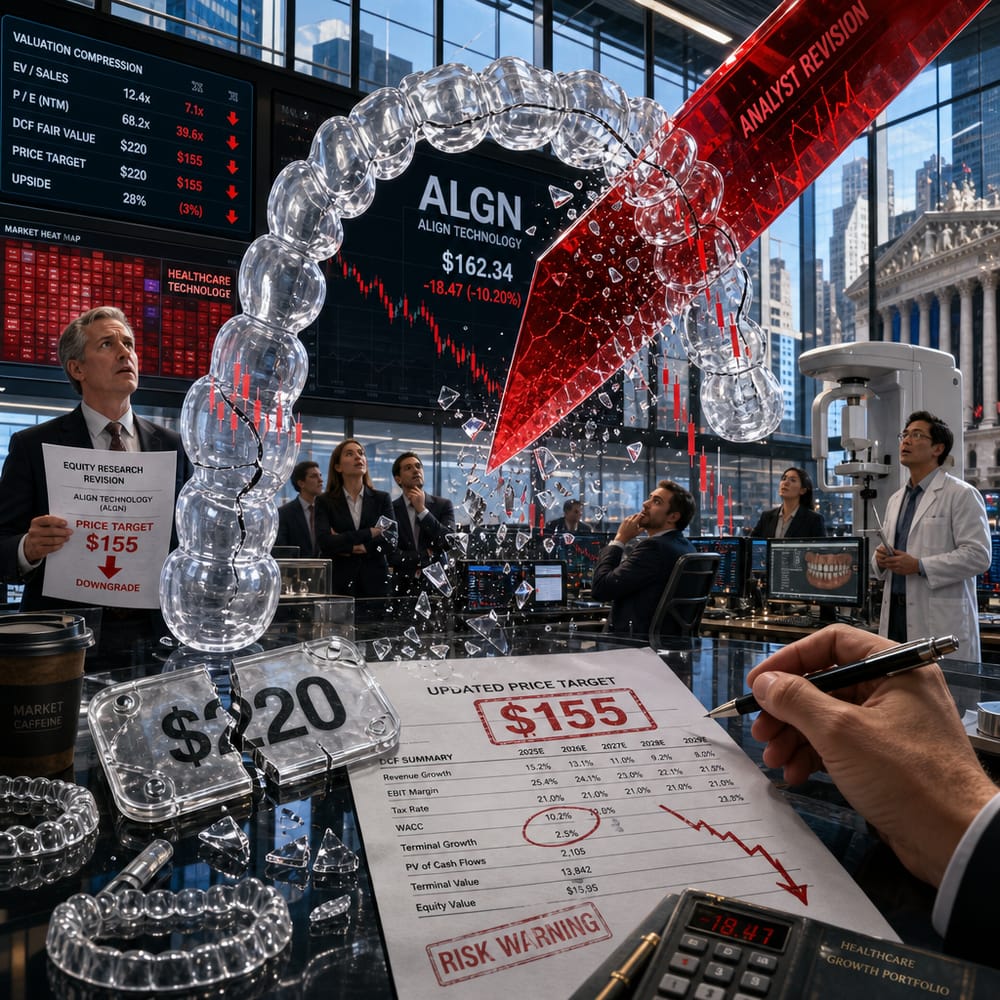
ALIGN TECHNOLOGY'S PRICE TARGET SLASHED: A VALUATION WARNING
Ever wondered what it feels like to hit a speed bump while cruising at 60 mph? Just ask Align Technology. Investors in this dental tech darling might need an aspirin after the somersault their stock just performed, with Evercore ISI taking a red pen to its price target, cutting it down from $220 to $155 faster than you can say "crowded orthodontist waiting room."
So, why the dramatic downgrade? It's not like braces have gone out of style, right? Demand for Align's flagship Invisalign product remains solid, but Evercore's analysts are raising an eyebrow at its valuation, which they think is as inflated as a blow-up mattress on prom night. The stock has been trading at sky-high multiples, but the underlying growth just isn’t setting hearts aflutter in quite the same way.
Now, before you consider dumping your shares faster than last year's iPhone, let's break down the factors behind this sudden reality check. First off, Align's valuation has been, to put it mildly, a bit frothy. Investors have been willing to pay a premium for its growth story, but when growth doesn't quite hit the high notes expected, even the most steadfast fans can start to squirm in their seats.
Besides, the broader economic context hasn't done Align any favors. The recent jump in Treasury yields is like gravity, pulling top-heavy stocks back down to Earth. When it costs more to borrow money, companies with sky-high valuations can see their wings clipped pretty quickly.
So, how's this going to play out for Align's stock in the near term? Expect a rollercoaster ride. Market sentiment is a fickle beast, and such a sharp downgrade could trigger a sell-off as investors reassess what they're willing to pay for Align's growth prospects. If Align can't convince Wall Street that it's a growth stock worth an indulgent multiple, that price might keep heading south before it stabilizes.
But don't count Align out just yet. A comeback could be in the cards if a few key catalysts fall into place. For one, any innovation in their product line that captures the imagination—and wallets—of consumers could reignite excitement. Who doesn't want a perfect smile without a mouth full of metal? Also, the global market for dental aesthetics is still plenty ripe, especially if Align can expand its reach into emerging markets where straight teeth are becoming a must-have accessory.
Not to mention, Align's tech advantage in the clear aligner space is nothing to sneeze at. They've got an edge with their digital platform, which makes for a smoother customer experience than an old-school orthodontist visit. If they can leverage this to increase penetration in the professional dental sector, it could signal a turnaround.
On the flip side, risks remain. With economic uncertainty casting a shadow over consumer spending, high-ticket items like Invisalign might fall under the discretionary axe. Plus, competition isn't exactly napping—rivals like SmileDirectClub are hungry for a bigger bite of the market. If Align can't maintain its competitive edge, it could find itself in a tough spot.
So, what should the everyday investor take from this? Align Technology isn't a bust, but it's in a tough balancing act. If you're already in the game, it might be time to strap in and keep a vigilant eye on those earnings reports and market whispers. For those on the sidelines, this could be an opportunity to buy the dip—if you believe in Align's ability to bounce back and mouth off its critics.
In the end, the dental tech space is as dynamic as ever, with Align Technology right in the middle of the action. Whether it turns out to be a crown jewel in your portfolio or a lesson in market valuations, only time—and a little bit of luck—will tell.
This article is for informational purposes only and is not investment advice. Always do your own research or consult a licensed financial professional before making investment decisions.
© Copyright 2024. All Rights Reserved.
© Copyright 2024. All Rights Reserved.